Divorce Split Their Child’s Coverage. One Plan Finally Paid.
Eight occupational therapy visits produced $1,920 in bills after two health plans disagreed over which one was primary. A notebook helped one parent pin down the coordination-of-benefits problem.
 Daniel ReyesNarrator, Navigating Care
August 29, 2026 · 7 min read
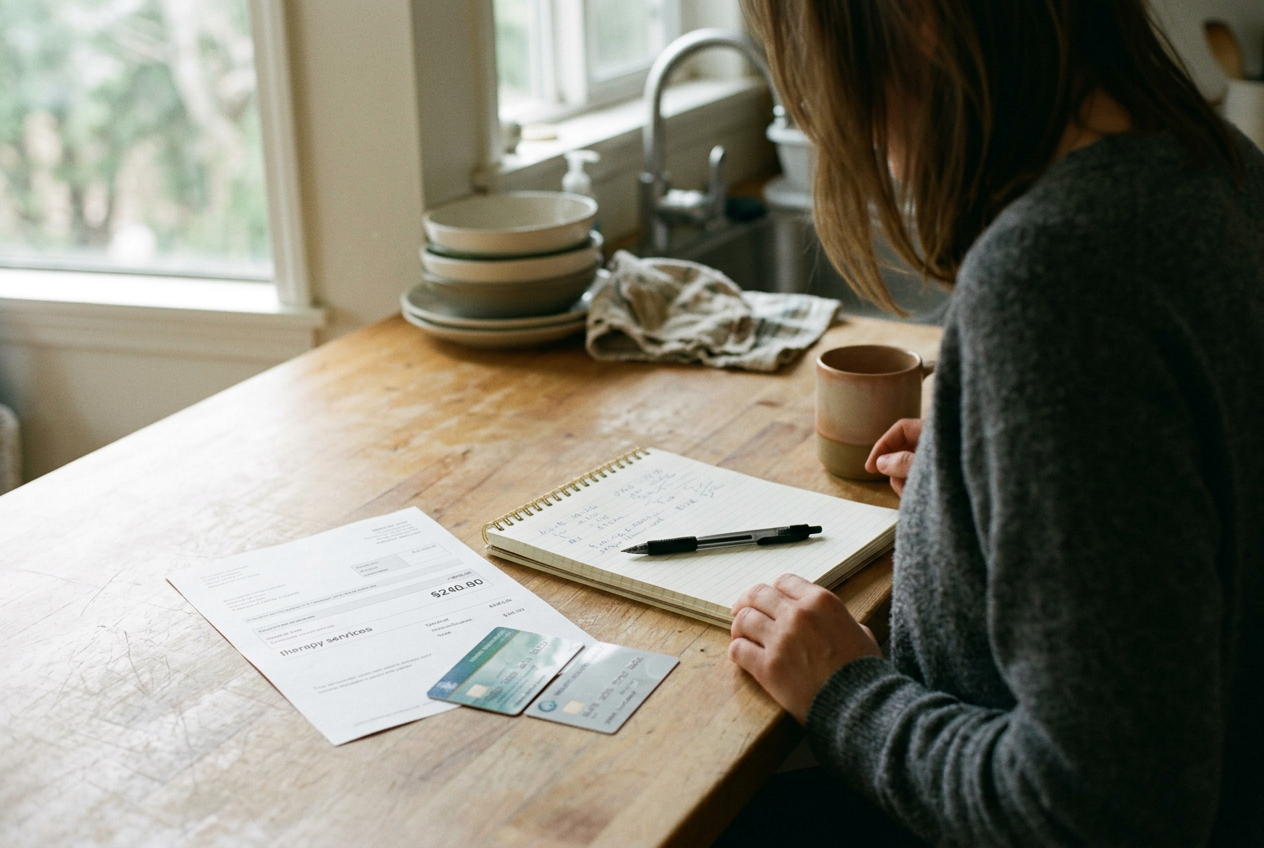
The first bill arrived four weeks after Maya’s divorce became final. Her son Eli had been seeing an occupational therapist for help with tasks that were frustrating him at school and at home, and the visits had continued through the separation because neither parent wanted the treatment room to become another place where the divorce took over.
The amount due was $240.
Maya opened a notebook and wrote down the date, the charge and the explanation from the therapy practice: the insurer had rejected the claim because its records showed another health plan should pay first. Eli was covered under both parents’ employer plans. Before the divorce, one plan had processed the visits without much trouble. Now each insurer seemed to be pointing toward the other.
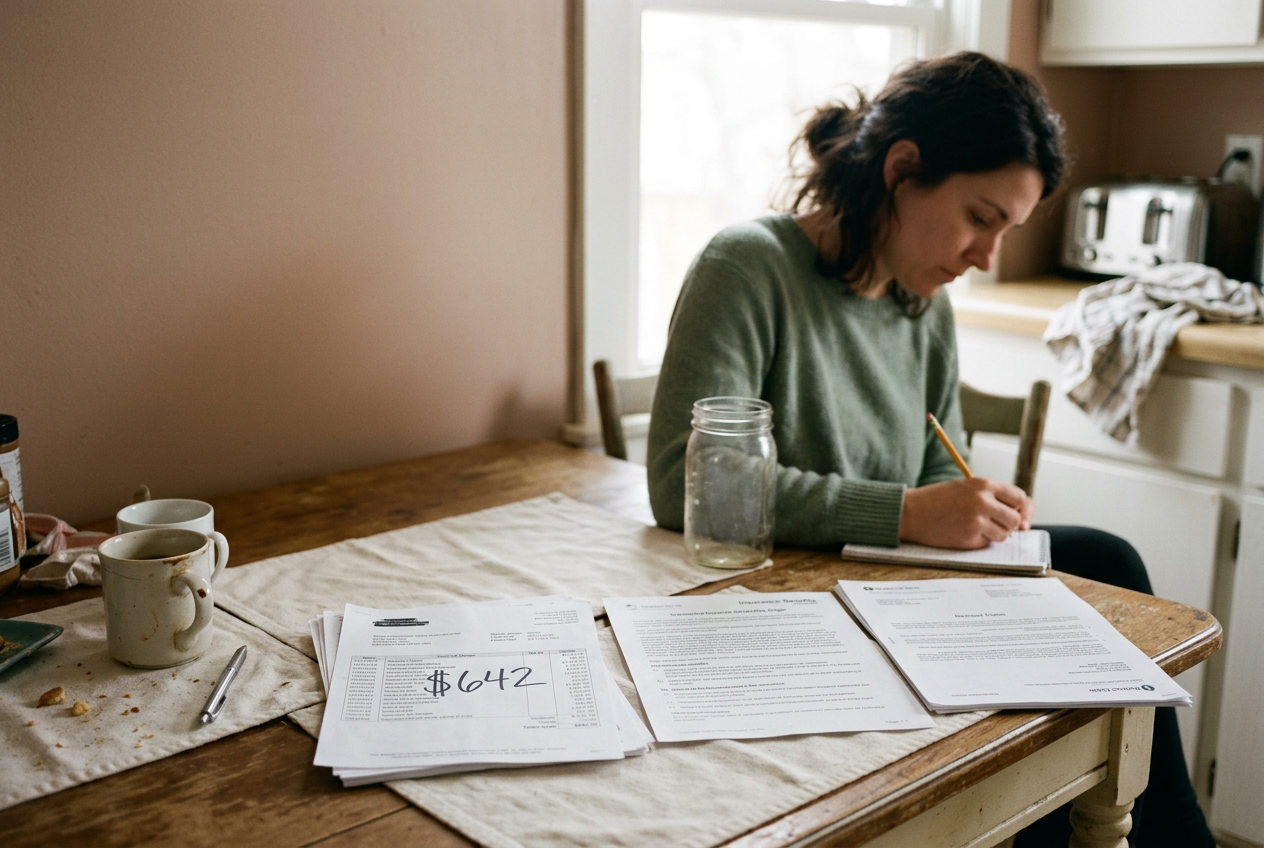
Maya paid the practice’s usual visit charge for the next appointment while the billing office tried again. Then another $240 appeared. Within two months, eight visits sat unpaid, leaving a total balance of $1,920.
The notebook filled with entries. She recorded which plan she had called, what documents it requested and whether the representative said its system listed the plan as primary or secondary. She did not write down every sentence. She wrote down the contradictions.
The rule changed, but the records did not
Coordination of benefits is the insurance term for deciding payment order when a person has more than one health plan. One plan is primary and considers the claim first. The secondary plan may then consider some of what remains, depending on its rules, the service and the patient’s cost sharing.
The phrase sounds cooperative. In practice, no joint conversation necessarily occurs. Each insurer maintains its own records, asks its own questions and can suspend or deny claims when those records conflict. The therapy practice submits a bill, receives a rejection and tries to work out which card belongs in the first position.
For children covered by two parents, many plans use a birthday rule while the parents are married: the plan belonging to the parent whose birthday falls earlier in the calendar year pays first. The parents’ ages do not decide it. That rule is often misunderstood, and it may stop applying after separation or divorce.
Divorce adds another layer. A court order may assign responsibility for the child’s health coverage. If it does not settle payment order, many plan documents use a sequence tied to custody: the custodial parent’s plan may pay first, followed by a plan covering that parent’s spouse, then the noncustodial parent’s plan. Plan language and state rules can differ, which is why a general explanation from a representative is not the same thing as a decision on a specific child’s coverage.
Maya’s divorce paperwork said both parents would maintain available health insurance for Eli, but it did not spell out which plan was primary. The insurers still needed to know that the parents were divorced, where Eli lived and whether another adult’s plan covered him. One plan had the divorce update. The other still treated the parents as married.
That mismatch was the whole blockage.
Maya circled two entries in the notebook. On one page, her insurer said its records made the other parent’s plan primary. Several pages later, the other plan said Maya’s coverage should pay first under its post-divorce rules. Neither statement moved the claims, and the billing office could not override either insurer’s enrollment record.
The unpaid claims reached the therapy room
The occupational therapist did not discuss the parents’ coverage dispute with Eli. Maya and her former spouse had agreed that insurance messages would stay between the adults, although that agreement became harder to keep as the balance climbed and each new visit created another claim that might be rejected.
The practice was not threatening to end care immediately. It also could not continue adding $240 charges without a payment plan or a clear path to insurance processing. Maya heard the distinction. Eli heard that his next appointments were being moved.
His therapy paused after eight unpaid visits.
This is where an administrative problem became a care problem. The insurer had not issued a clinical denial saying occupational therapy was unnecessary. It had not reached that question. The claims stopped earlier because the plans disagreed over payment order, leaving the family with bills and the child without his regular sessions while everyone worked on the insurance records.
Maya’s former spouse initially read the denials as evidence that her plan had failed. She read his insurer’s messages the same way. The notebook complicated both versions, because the entries showed that each company had incomplete information and each parent had supplied only the documents requested by the plan connected to their own job.
They shifted to one narrow task. Maya became the contact for the therapy practice, and each parent handled enrollment questions from their own insurer. Copies of coverage messages went into a shared email thread that did not include arguments about the divorce. It was an awkward boundary, but it kept the dispute away from Eli’s therapist and reduced the chance that one parent would promise the practice something the other insurer had not confirmed.
The consequential document was not a medical record. It was proof that the parents’ marital and custody information had changed. Maya sent the material her plan requested and asked it to review the child’s coordination-of-benefits status from the month the divorce became final. Her former spouse supplied his plan with the same basic change in circumstances.
Then they waited.
One plan finally accepted first position
Six weeks after the therapy stopped, Maya added a new line to the notebook. Her insurer had updated Eli’s record and determined that Maya’s plan was primary from the applicable post-divorce date. The other parent’s plan was secondary.
That decision did not pay the bills by itself. The therapy practice still had to submit the eight claims to Maya’s plan in the correct order, wait for the primary explanations of benefits and then send any eligible remaining amounts to the secondary plan. Claims that had already been rejected needed reprocessing rather than another copy of the same submission.
The distinction mattered. Resubmitting an unchanged claim can produce the same rejection because the insurer still sees the original problem. Reprocessing meant the plan reconsidered the existing claim after its coordination-of-benefits record had been corrected.
Over the next five weeks, the $1,920 patient balance changed in stages. The primary plan applied its contracted rate and paid its share. The secondary plan considered the remaining amounts after receiving the primary plan’s decisions. Maya still owed the cost sharing assigned under the coverage, but she no longer owed the practice’s full charges for all eight visits.
She kept checking the notebook against the insurer portals and the practice statements, looking for the same visit to appear under different amounts. One claim lagged behind the others because it had not entered the second round of processing. The billing office sent that one back after the updated coverage order was visible.
Eli returned to occupational therapy after a pause of nearly three months. His therapist did not need the notebook, the divorce documents or the explanations of benefits. The session resumed with the work they had been doing before the claims stopped.
What worked for Maya was not a persuasive appeal about Eli’s need for therapy, because the insurers had never evaluated that issue. She documented the conflicting payment-order statements, got both plans to update the same family facts and waited for the primary plan to process each claim before the secondary plan considered it.
The notebook stayed on the kitchen counter until the last $240 charge disappeared from the practice’s unpaid-claims list.
Questions people ask
Which parent’s insurance is primary after a divorce?
In this family’s case, the insurers looked at the divorce and custody information after the decree took effect, and Maya’s plan became primary. Many plans follow an order based on a court decree or custody, but the plan documents and applicable rules control; the birthday rule used for married parents may no longer decide payment order.
Why would both insurers refuse the same therapy claim?
Both plans can hold or reject a claim when their records indicate that another insurer must consider it first. Eli’s occupational therapy was interrupted because one company had updated divorce information and the other still treated his parents as married, not because either plan had completed a medical review of the therapy.
Will the secondary plan pay whatever the primary plan leaves behind?
Not necessarily. In this story, the secondary plan considered the balance only after it received the primary plan’s decision, and Maya still owed the cost sharing assigned under the coverage. Secondary insurance does not automatically erase deductibles, copays or every unpaid charge.
Can denied claims be reconsidered after coverage records are corrected?
Eli’s eight claims were reprocessed after the primary plan corrected its coordination-of-benefits record. The therapy practice submitted them in payment order, then sent eligible remaining amounts to the secondary plan. Maya kept the notebook open until the final visit matched the revised practice statement.
One story a day
The story of the day, in your inbox
One health journey each morning — no advice, no alarm, just company for the road.