A Newborn Enrollment Appeal Cut a $47,892 Bill to $2,184
The hospital had the baby’s insurance information. The health plan did not have the baby. Fixing that distinction took a late-enrollment appeal and six weeks.
 Daniel ReyesNarrator, Navigating Care
September 6, 2026 · 8 min read
The first number that made sense was $47,892.
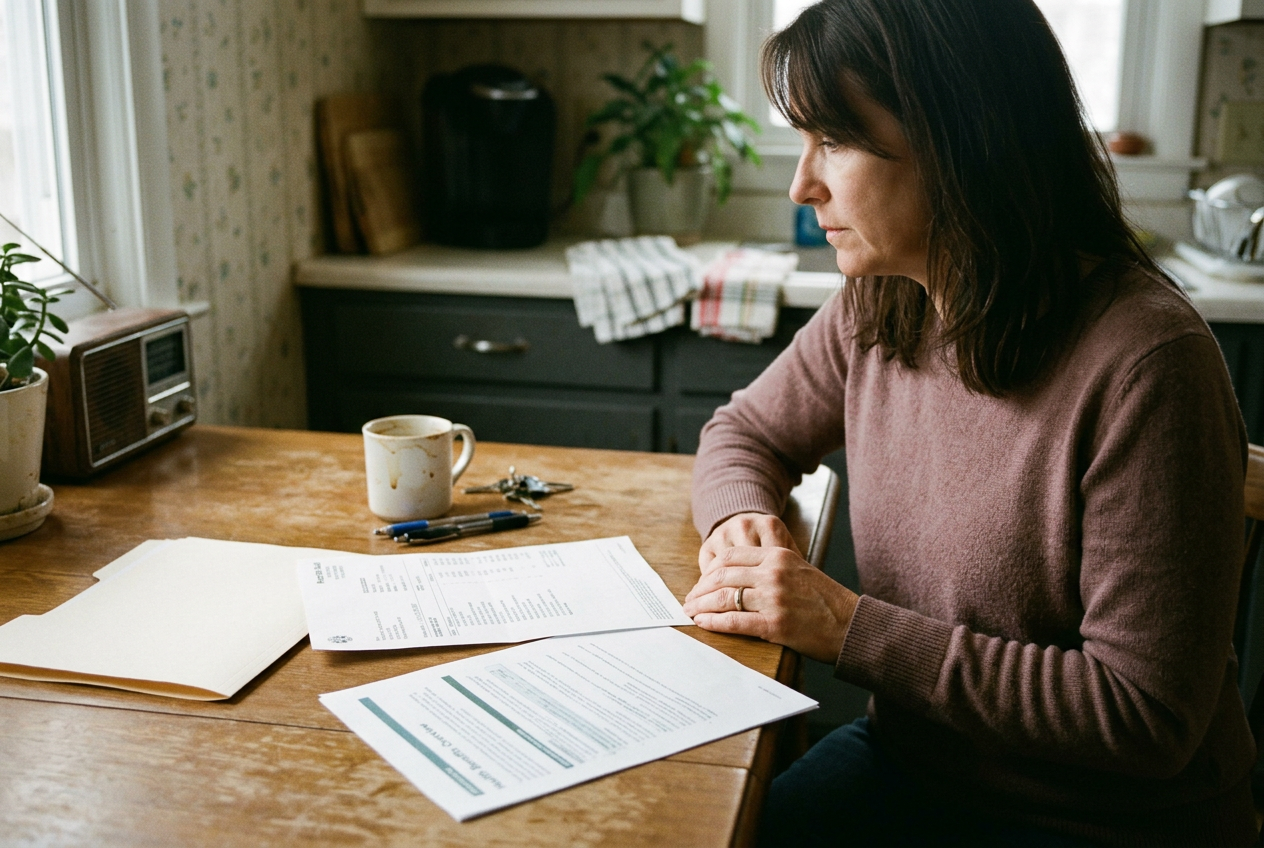
It appeared on an itemized hospital statement seven weeks after their daughter was born. The mother had experienced a complicated delivery, and the baby had remained in the hospital for six days of monitoring and treatment. Insurance payments on the statement showed zero. The full balance sat under the amount assigned to the family.
Her husband assumed the claims were still processing. During the hospital stay, he had given the billing office the same insurance information used for the delivery. After they returned home, he opened his employer’s benefits portal, entered the baby as a dependent, and uploaded proof of the birth. A confirmation screen appeared.
He saved a screenshot and went back to caring for an infant while his wife recovered.
That action created a dependent record. It did not enroll the dependent in medical coverage.
This is the kind of distinction benefits systems treat as obvious, although it is obvious mainly to people who administer benefits systems. The hospital can record that a baby is expected to have insurance. An employer can verify that the baby is an eligible dependent. The health plan can still have no active coverage for that child because nobody completed the separate coverage election.
By the time the parents understood that, the employer plan’s special enrollment window had closed.
The missed step was not a claim problem
The father first called the insurer using the number on the back of his card. The representative could see coverage for both parents but no enrollment record for the newborn. The hospital had submitted the baby’s claims under her own patient record, as it should have, but the insurer could not match those claims to an eligible member.
The billing office described the claims as pending. The insurer described the baby as absent from eligibility. The employer’s benefits office described the enrollment as incomplete. All three statements could be true, and none told the parents who had the authority to fix the underlying problem.
They kept returning to the $47,892 statement, which was now accompanied by smaller statements from clinicians involved in the hospital care. Appealing each claim would not solve much. The insurer had not reviewed the services and decided they were excluded or medically unnecessary. It had no enrolled member against whom to process them.
The useful distinction was eligibility versus claims. Eligibility determines who is covered and for what dates. Claims processing determines how the plan handles bills for someone already listed as covered. Their problem sat upstream, with enrollment, even though the most alarming evidence arrived from billing.
Federal special enrollment rules generally require employer group health plans to allow at least 30 days after a birth for an eligible employee to request enrollment for the child. When the request is made on time, coverage for a newborn generally takes effect as of the date of birth. Marketplace plans generally provide a 60-day special enrollment period around a birth, with coverage usually available from the birth date. Medicaid and the Children’s Health Insurance Program accept applications year-round, subject to eligibility rules.
Those public deadlines sound generous until they overlap with surgery, feeding problems, discharge instructions, pediatric visits, sleep measured in fragments, and a portal that treats dependent verification and health coverage as separate transactions. A birth certificate or hospital record proves the relationship. It does not, by itself, tell an employer which benefits the parent elected.
Some plans or state laws provide temporary newborn coverage under certain circumstances, but parents cannot assume that every baby is automatically and permanently added to a parent’s policy. Temporary coverage, notice of birth, and completed enrollment are different things. The jargon hides that separation.
They appealed the enrollment, not the hospital bill
The father’s screenshot became the important artifact. It showed that he had entered the portal 24 days after the birth, within his employer plan’s special enrollment period, and submitted the dependent documentation. It did not prove he completed the medical election, but it did establish that he had tried to act while the window remained open.
He made a short chronology covering the delivery, the baby’s six-day hospital stay, his wife’s recovery, the portal submission, and the date they first learned that coverage had not been activated. He attached the screenshot, discharge records that confirmed the hospital stays, and the $47,892 statement. He did not argue about whether the hospital care should be covered. He asked the employer’s plan administrator to accept a late enrollment correction and make the baby’s coverage effective from birth.
That target mattered because the employer sponsored a self-funded health plan. In that arrangement, an insurance company may run the network, issue explanations of benefits, and process claims, while the employer’s plan administrator retains authority over at least some eligibility decisions. The name on the insurance card is therefore not always the organization that can add a dependent after a deadline.
Under a fully insured plan, responsibilities can be divided differently. The plan documents and enrollment materials govern. In this family’s case, repeated calls to the claims side produced notes but no enrollment because the claims representatives could not create eligibility that the employer had never transmitted.
The first response upheld the missed deadline. It treated the request as though the father had done nothing during the enrollment period, which ignored the screenshot and the reason the process stopped. He sent a second written request through the benefits office, again asking for an eligibility review rather than a claim adjustment, and emphasized that the portal had accepted the dependent documentation without making clear that another election remained unfinished.
This was not a guaranteed exception. Federal special enrollment rights are powerful when a complete request is made within the applicable window, but they do not create an unlimited extension whenever a family discovers an omission later. Plans may have correction procedures or discretion to review late requests, especially when records show a timely attempt, an administrative problem, or circumstances that interfered with completion. Whether that review exists depends on the plan and the facts.
The parents also asked the hospital to hold the account while eligibility was under review. The billing office did not erase the balance, and it did not promise that coverage would appear. It paused further billing activity for a limited period and noted that the claims could be resubmitted if the baby became active retroactively.
For six weeks, the $47,892 statement stayed in a folder beside the portal screenshot. The parents added each benefits message and hospital notice to the same folder, partly because different offices kept asking for the same information and partly because exhaustion had already exposed the cost of relying on memory.
Retroactive coverage did not mean a free hospital stay
The plan administrator approved the late enrollment correction. The baby’s effective date was set to her birth date, and the employer collected $436 in retroactive family premiums over two paychecks.
Approval did not move the hospital claims automatically. The corrected eligibility first had to reach the company that processed claims. The hospital then resubmitted its claims, and separate clinician bills followed. For a while, the insurer’s portal showed active newborn coverage alongside claims that still looked unpaid, another overlap between systems that had updated at different speeds.
New explanations of benefits arrived about a month later. Network discounts reduced the allowed amounts, the plan paid its share, and deductible and coinsurance rules assigned $2,184 to the family. That figure was painful. It was also different from $47,892, which had represented an unresolved gross charge rather than the family’s final responsibility under the plan.
The hospital statement came last. It showed the insurance adjustments and the remaining $2,184 balance. The father compared it with the original page line by line before moving it into the folder.
What worked for this family was narrow: proof of a timely attempt, a written request aimed at the entity controlling eligibility, and enough follow-through to get the claims resubmitted after coverage changed. Another plan could reach a different result on a late request. Their win began when they stopped treating the $47,892 statement as the problem itself and used it as evidence of what the failed enrollment had set in motion.
Questions people ask
Is a newborn automatically covered by a parent’s insurance?
Not in every plan, and not permanently without enrollment. Employer plans generally must offer at least 30 days for special enrollment after birth, while Marketplace plans generally allow 60 days. In this family’s case, giving insurance details to the hospital and verifying the child as a dependent did not complete the medical coverage election.
What happens if the newborn enrollment window has already closed?
A late request can be denied, although some plans review corrections or exceptions based on their terms and the circumstances. This family asked for an eligibility appeal and supplied evidence that the father had started the process within the window, along with records showing the complicated delivery and newborn hospital stay.
Why did the hospital bill show the full charge instead of an insurance rate?
The insurer could not process the claims under plan benefits while the baby was missing from its eligibility file. The hospital statement therefore showed $47,892 before network adjustments or plan payments. Once retroactive coverage appeared and the claims were resubmitted, the family’s responsibility was recalculated under the deductible and coinsurance rules.
Who can fix missing newborn coverage?
That depends on who controls eligibility under the plan. Here, the insurer processed claims, but the employer’s plan administrator decided the late-enrollment request and transmitted the corrected coverage dates. The parents kept the revised hospital statement showing $2,184 in the same folder as the original $47,892 page.
One story a day
The story of the day, in your inbox
One health journey each morning — no advice, no alarm, just company for the road.