The Insurer Denied Proton Therapy. Their Town Raised $42,000
A denial put a child's radiation plan and her family's finances at risk. They tracked every cost in a notebook while neighbors raised money and an independent reviewer reconsidered the case.
 Daniel ReyesNarrator, Navigating Care
August 21, 2026 · 7 min read
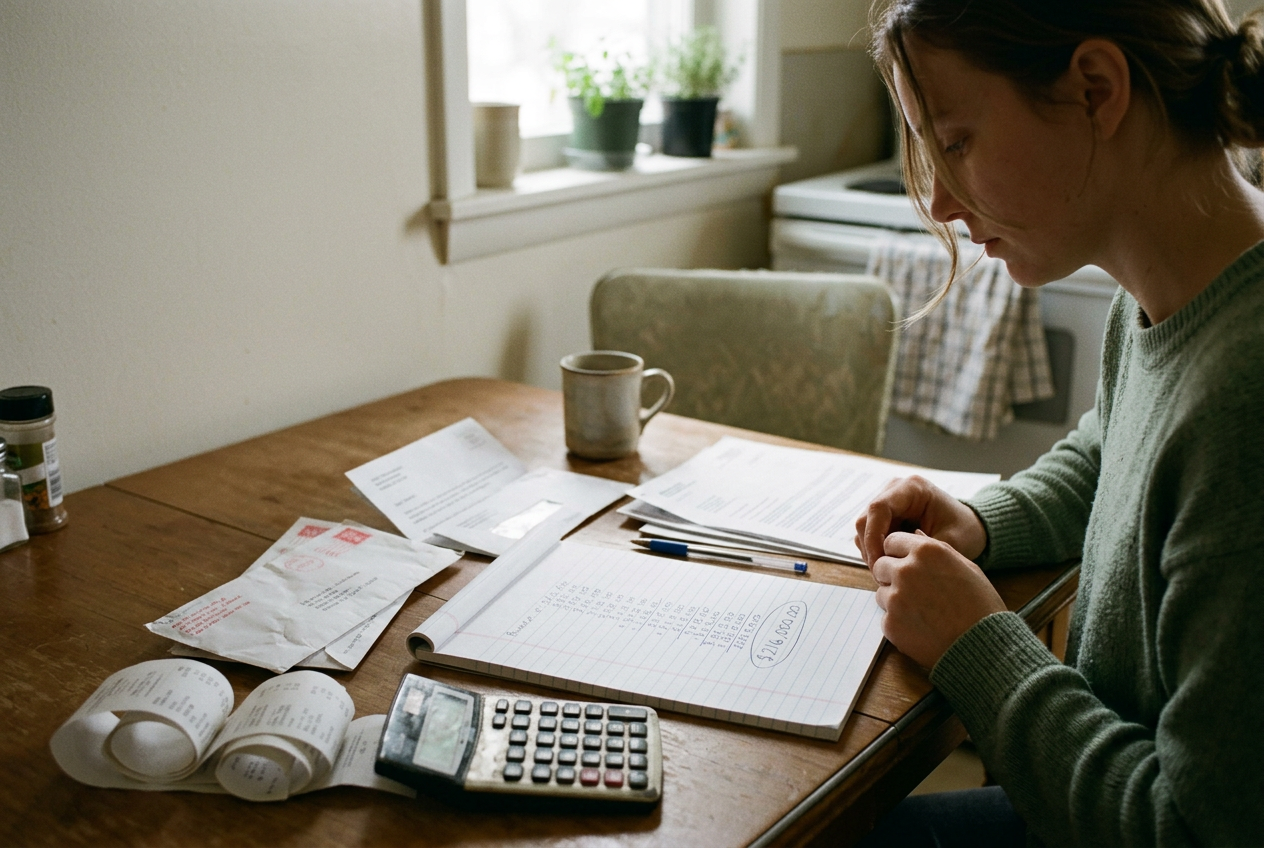
The notebook started with one number: $216,000.
That was the hospital’s estimate for proton radiation after the family’s insurer denied authorization in February 2022. The amount was not an itemized bill, and nobody expected the insurer to pay the full sticker price if coverage came through. It was still the only number the family had for what treatment might cost without insurance.
Their daughter had undergone surgery for medulloblastoma weeks earlier. Her specialist recommended proton therapy for the radiation portion of her treatment, including radiation along the brain and spine. The goal was not to test whether radiation worked. Radiation was already part of the treatment plan.
The specialist believed protons could reduce unnecessary exposure to healthy tissue compared with the photon plan available to her.
The insurer labeled the proton treatment investigational.
That word did financial work. It converted a specialist’s recommendation into a service the plan could refuse to pay for, leaving the family to choose among delay, a different radiation plan or a price larger than their mortgage balance. “Investigational” sounded as if their daughter had been invited into an experiment. What the policy language was hiding was a dispute over whether this more targeted way of delivering radiation met the plan’s coverage rules for this child.
The mother wrote the estimate in a notebook she had been using for medication changes and questions for appointments. Beneath $216,000, she added the family’s available savings: $11,400.
There was no version of the math that worked.
Two tracks at once
The specialist’s office submitted an urgent appeal. The family sent permission for the doctor to share records, then kept calling the number on the back of the insurance card to confirm that each packet had arrived. The appeal included the diagnosis, the proposed radiation plan and medical literature supporting proton therapy for children whose developing tissue could receive less unnecessary radiation.
A treatment comparison mattered most. The hospital had produced plans showing how much radiation surrounding parts of the body would receive under proton and photon approaches. The point was specific to this child: both plans were intended to treat the necessary areas, but one reduced dose outside them.
The first internal appeal was denied 11 days after the original decision.
Meanwhile, the notebook had changed. Its pages now held the date of each insurer conversation, the role of the person who answered and a short account of what that person said. The mother did not try to transcribe every exchange. She needed enough to track whether the appeal was pending, denied or missing, distinctions that became absurdly difficult to establish as the treatment window narrowed.
She also began writing down costs. Travel to the radiation center would require temporary lodging because the facility was several hours from home. Her husband had paid leave, but not enough for the full treatment period. She had already stopped working after the surgery.
Their health plan’s deductible and coinsurance still applied even if the denial was overturned.
The notebook separated those expenses from the $216,000 estimate. That decision changed how the family asked for help.
A relative created an online fundraiser with the family’s permission, while a neighbor coordinated community aid so the parents did not have to answer every message. The public explanation stayed plain: a child needed specialized radiation, insurance had denied it and the family faced travel and lost income while appealing. They did not publish medical records or the denial letter.
In six weeks, 614 people contributed $42,186.
Some donations were $10. One was $5,000. A local group covered part of the lodging bill directly, which meant the family did not have to put that amount on a credit card while waiting for fundraiser transfers. Other help arrived as gas money and meals, but the family counted only the cash contributions in the fundraiser total.
This was generous. It was also evidence of a broken arrangement. Neighbors were financing the delay created by a coverage dispute they had no power to decide, while the insurer continued evaluating whether a child’s prescribed radiation qualified under language few families would understand on the first reading.
The fundraiser could not solve a $216,000 treatment estimate. It could keep the rest of the household from collapsing while the appeal moved.
What the outside review changed
After the internal appeal failed, the case went to an independent medical review available under the family’s plan. The specialist’s office marked the request urgent and resubmitted the clinical comparison, along with records showing why radiation could not be postponed for a routine review period.
The parents were not writing a medical argument from scratch. That distinction mattered. Their job was to keep the case moving and document what had been sent; the specialist’s job was to explain why this treatment was medically appropriate. Families are often told to advocate for themselves as though determination can substitute for access to clinical evidence.
It cannot.
Nine days later, the outside reviewer overturned the denial.
The insurer authorized proton therapy under the plan’s regular cost-sharing rules. The decision did not say proton therapy was now covered for every person with medulloblastoma. It found that the proposed treatment met the standard for this patient, based on her age, diagnosis and radiation plan.
The family never paid $216,000. That number had been the hospital’s estimate before insurance, not the final negotiated amount, and the insurer’s explanation of benefits later showed a lower allowed charge. The family still owed its deductible and coinsurance, which reached $8,700 for the year.
Coverage ended one emergency. It did not refund the cost of having the emergency.
By the end of treatment, the notebook showed $4,836 for lodging after community assistance, $2,119 for travel and parking, and $9,840 in lost wages. There were smaller medical bills from other parts of care. The parents stopped trying to assign every grocery purchase to cancer, though eating away from home had plainly raised their spending.
Fundraiser money covered the lodging, travel and most of the health plan cost-sharing. The remainder stayed in a separate account for follow-up care until the organizer closed the campaign and posted a final update. The family reported the total to a tax preparer because online donations can create questions even when they are intended as personal gifts.
The label was not the last bill
Treatment began 24 days after the original denial. The mother carried the notebook to the temporary apartment and kept using it, although the pages about insurer calls became less frequent. Treatment dates took their place. Then came explanation-of-benefits notices, hospital statements and a refund from one office that had collected too much up front.
The parents had won the coverage fight. They were still sorting bills eight months later.
Financial toxicity is the term researchers and hospitals use for the harm caused by the cost of care. The jargon can make it sound like a side effect confined to a spreadsheet. In this family, it meant leaving work, watching a credit card balance rise and asking acquaintances for money while their daughter was recovering from brain surgery and starting radiation.
Community aid softened that harm because one person outside the immediate family managed the requests and because donors could see the concrete gap they were filling. The appeal worked for a different reason: the independent reviewer received a patient-specific comparison from the specialist showing why the proposed radiation plan met the child’s needs.
Neither track replaced the other. Insurance eventually paid for the authorized treatment. The community paid for much of what insurance never considered treatment at all.
Questions people ask
Why would an insurer call proton therapy investigational for medulloblastoma?
In this case, the label came from the plan’s coverage criteria, not from a claim that radiation itself was untested. The dispute concerned whether proton delivery was medically necessary for this child rather than a covered photon approach. The outside reviewer reached a different conclusion after examining her specialist’s comparison of the plans.
Can an urgent insurance appeal be decided before treatment starts?
This family received an internal denial after 11 days and an outside decision nine days after requesting independent review. Treatment began 24 days after the original denial. That timing reflected the specialist’s urgent submission and the plan’s review pathway; the story does not show that every plan or case moves at the same speed.
Did the fundraiser pay the $216,000 treatment estimate?
No. The insurer reversed its denial and covered proton therapy under the family’s usual benefits, so the family did not pay the hospital’s original estimate. The $42,186 fundraiser covered much of their cost-sharing, temporary lodging and travel, along with income lost while a parent remained away from work.
What expenses remained after the denial was overturned?
Authorization did not erase the deductible, coinsurance or nonmedical costs. The family recorded $8,700 in annual cost-sharing, $2,119 for travel and parking, and $9,840 in lost wages. Eight months after treatment began, the notebook’s lodging page still ended with $4,836.
One story a day
The story of the day, in your inbox
One health journey each morning — no advice, no alarm, just company for the road.