A Student’s $2,184 Ambulance Bill Went to His Parents
He got the charge reduced to $219. Stopping future health notices from going to the policyholder parent took a separate privacy request and six more weeks.
 Daniel ReyesNarrator, Navigating Care
August 28, 2026 · 7 min read
Jordan was 21, living away at college and paying his own rent when campus staff called an ambulance for him in October 2024. He had become disoriented and unsteady. The emergency department monitored him, ruled out an immediate crisis and released him.
Six weeks later, his mother sent him a photograph of an itemized ambulance bill that had arrived at his parents’ house. The total at the bottom was $2,184.
The bill was addressed to Jordan, but it used the family home as his mailing address. A separate explanation of benefits had gone to his father, the policyholder. Between the two documents, his parents could see that he had received emergency transportation, where the ambulance had taken him and how much the service cost.
Jordan had not told them about the episode.
He was financially independent in every way that mattered to his daily life. He worked during school, filed his own taxes and paid his living expenses. None of that changed how the health plan’s computer saw him. He was an adult dependent attached to his father’s employer coverage, and the policyholder’s address had become the default destination for paperwork about his care.
That is the first piece of jargon worth translating. “Dependent” describes enrollment under an insurance policy. It does not mean the adult patient has surrendered privacy rights or needs a parent’s permission to discuss personal care. Yet insurance systems often route explanations of benefits to the person who holds the policy because those notices explain how shared deductibles and plan benefits were used.
The system had made his private emergency visible without asking whether visibility was safe, wanted or even relevant.
The bill showed two separate problems
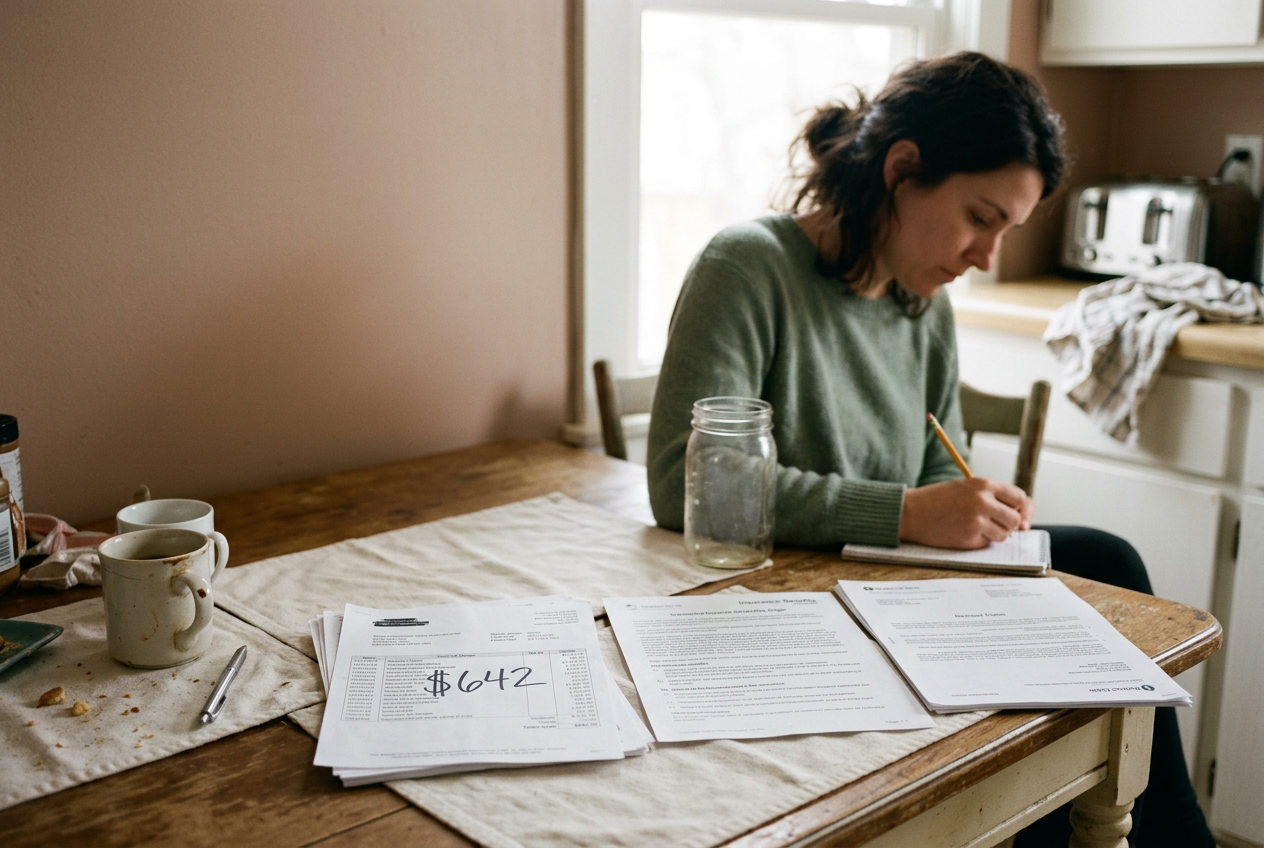
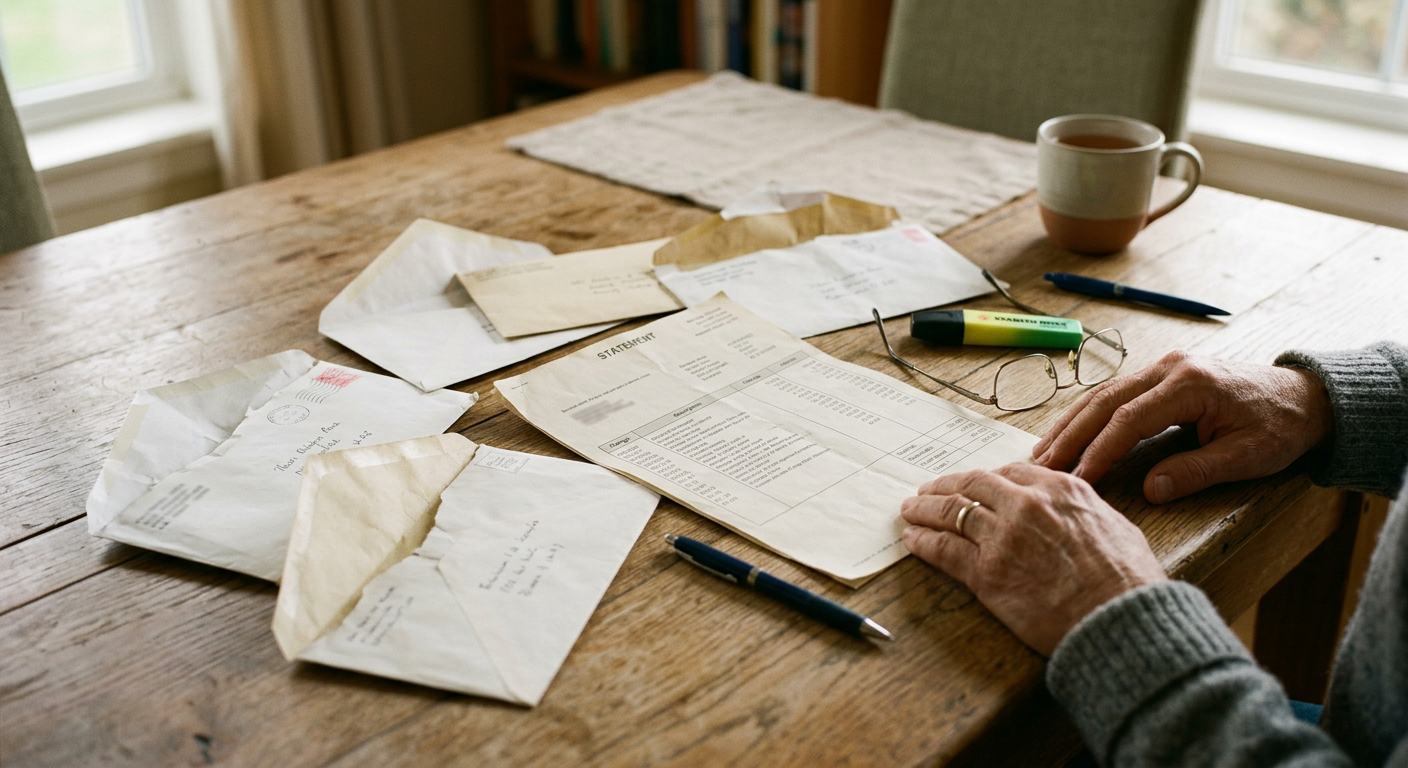
When the paper bill reached Jordan by mail, he kept it beside his laptop and circled the $2,184 total. There was no insurance payment listed. The balance was marked as his responsibility.
His online insurance account showed that the ambulance claim had been denied pending more information about why emergency transportation was required. The ambulance service, meanwhile, had used the address it received during billing and sent the full charge there.
One document had created two jobs. Jordan needed to challenge the unpaid claim, and he needed to stop future notices from traveling to his parents’ house. Fixing one would not fix the other.
The distinction is easy to miss because patients experience insurance and provider billing as one machine. They are separate record systems. An address change with the health plan may not update the ambulance service, hospital or other provider, while changing a billing address with a provider does nothing to alter where the insurer sends an explanation of benefits.
Jordan first called the number on the back of his insurance card. He asked why the claim had not been paid and said future information about his care could not go to the policyholder’s address. The representative treated the second request as an ordinary address change and told him the main policy address belonged to his father.
That answer hid the real option. Jordan was not trying to move the entire family policy. He was asking the plan to communicate with an adult member at an alternate address.
Federal health privacy rules let patients request confidential communications through another method or at another location. Health care providers generally must accommodate reasonable requests. Health plans have a narrower federal obligation tied to a person stating that disclosure could endanger them, although plan procedures and state protections can offer more room.
Jordan used the plan’s general privacy request process, gave his campus mailing address and asked for electronic claim notices when available. He also stated that sending information about his care to the policyholder’s home could put him at risk. The request concerned communications about his claims, not a change to his father’s employer enrollment.
The plan warned that some policy-wide material would still go to his father. That remained unresolved. Jordan’s immediate concern was more specific: service-level notices that revealed when and where he received care.
The money appeal moved on a different track
The itemized bill stayed open beside him while he contacted the ambulance billing office. He corrected his mailing address, asked the office to pause collection activity during the insurance review and confirmed that it had the right coverage information.
Then he appealed the denial through the insurer. His submission was short. He explained that campus staff had called for emergency transport after observing his condition, and he included the emergency department discharge summary with the itemized bill. Those records showed what happened without requiring him to supply private details that had nothing to do with whether the transportation benefit applied.
Five weeks later, the insurer reprocessed the claim under the plan’s emergency ambulance coverage and paid $1,542. The ambulance billing office adjusted $423 after reviewing the new payment. Jordan’s remaining coinsurance was $219.
The arithmetic mattered: $1,542 paid, $423 adjusted and $219 left for Jordan equaled the original $2,184 charge.
Ground ambulance billing has a particularly ugly gap. Federal protections that limit many surprise out-of-network medical bills generally do not apply to ground ambulances, so a patient can still face a charge above what an insurer recognizes. Jordan’s result came from the terms of his own plan and the ambulance service’s adjustment after reprocessing. It was not a universal cap.
He wrote the new figures on the itemized bill and saved the updated insurance notice. The paper that had first exposed the emergency to his parents now documented the financial result, but it said nothing about whether the next claim would remain private.
The privacy correction took longer
Jordan checked the privacy request through his online account rather than assuming the first call had settled it. The plan asked him to confirm the alternate mailing information, and six weeks after his initial request, it marked the communication preference as active.
He also changed the contact information held by the hospital and ambulance billing office. That duplication was tedious, though necessary in his case, because each organization controlled its own outgoing mail.
Two billing cycles after the original $2,184 notice, the ambulance service mailed the revised statement to Jordan at school. The insurer posted its explanation electronically to his account. His father could still see that family plan dollars and deductible amounts had changed, which Jordan could not fully prevent while remaining on the same policy, but the detailed documents did not arrive at the family home.
Financial independence had never been the deciding factor. The useful steps were narrower: Jordan appealed the ambulance denial with records tied to the emergency, then treated confidentiality as its own problem and made separate communication requests to the organizations holding his address.
His experience did not produce perfect secrecy. Shared insurance leaves traces, especially when a family deductible or benefit limit changes. What worked for him was getting the claim reduced to $219 while forcing each record system to recognize that the adult patient and the policyholder were different people.
Questions people ask
Can an adult dependent keep insurance claims private from a parent?
An adult dependent keeps personal health privacy rights, but a policyholder may still receive explanations of benefits or see changes to shared plan spending. In Jordan’s case, a confidential communication request redirected detailed notices, although it did not hide every financial effect of using the family policy.
Does changing my address with the insurer update the ambulance company?
It did not in this story. The insurer, ambulance service and hospital maintained separate records, so Jordan changed his contact information with each organization that had sent or might send paperwork. His confidential communication request to the health plan covered insurer notices, not provider bills.
Are ground ambulance bills protected by the No Surprises Act?
Federal surprise-billing protections generally exclude ground ambulance services. Jordan’s $2,184 charge fell because his insurer reprocessed the emergency transport and the ambulance billing office made an adjustment, leaving $219, rather than because federal law imposed a standard limit.
What documents changed the ambulance claim result?
Jordan submitted the itemized ambulance bill and his emergency department discharge summary, along with a short account of why campus staff called for transport. Five weeks later, the revised paperwork showed a $1,542 insurance payment, a $423 adjustment and $219 remaining.
One story a day
The story of the day, in your inbox
One health journey each morning — no advice, no alarm, just company for the road.