A Transfer Record Cut Her $64,820 Air Ambulance Bill to $2,140
The flight was out of network, and the first insurance notice treated $64,820 as hers. One transfer record changed the coverage decision, allowing federal air ambulance protections to apply.
 Daniel ReyesNarrator, Navigating Care
August 24, 2026 · 8 min read
Mara was 31 weeks pregnant in September 2023 when heavy bleeding sent her to the small hospital near the ranch where she worked. The hospital could evaluate her, but it did not have the maternity specialists or newborn care that staff believed might be needed. A distant maternity center accepted the transfer.
Driving would have taken more than three hours. The hospital arranged a helicopter. Mara’s baby was delivered after they arrived and remained in the hospital for 18 days.
Six weeks later, while the baby was home and feeding every few hours, Mara opened an itemized bill for $64,820. The base charge was $38,900. Another $25,920 covered 144 flight miles at $180 per mile.
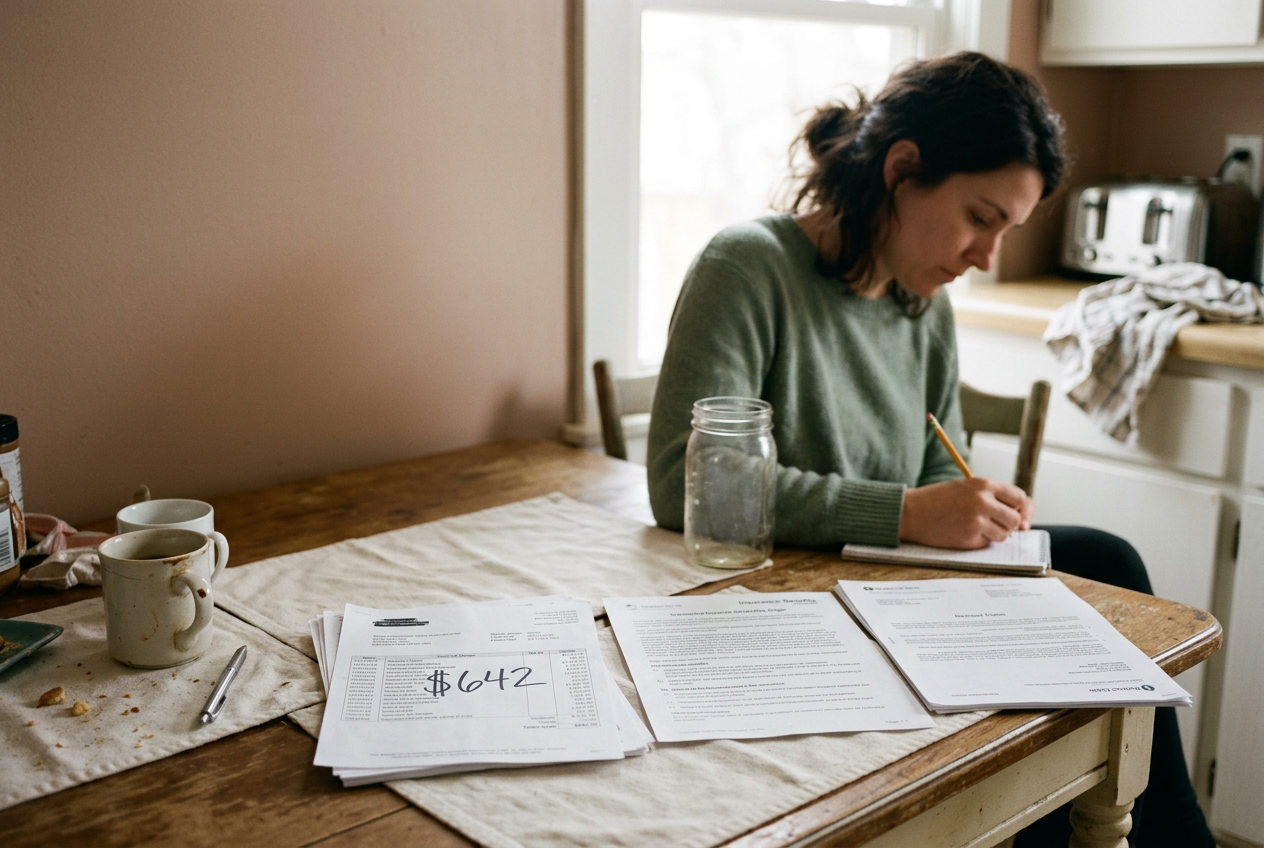
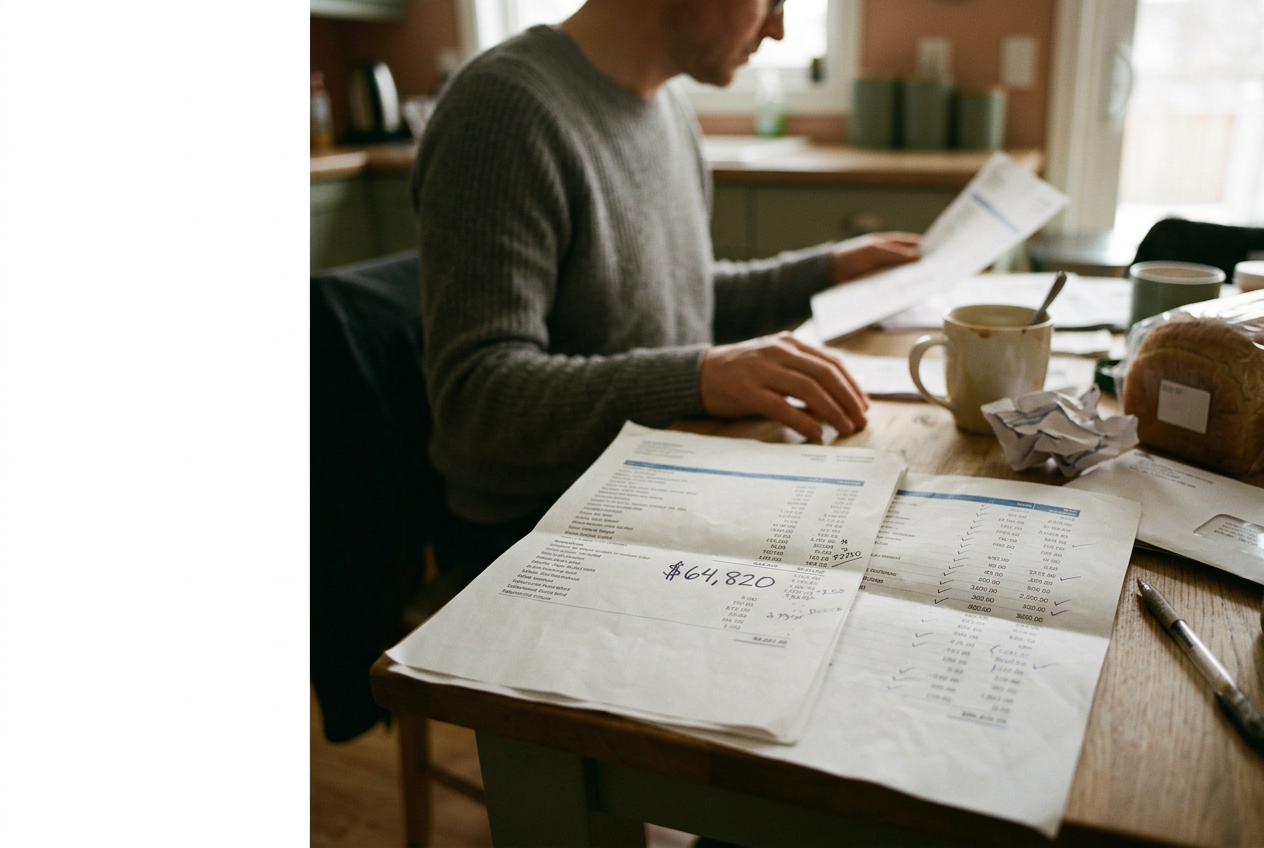
She kept that bill on the kitchen table. It became the one document against which every other explanation had to make sense.
None did.
The $64,820 mismatch
The insurer’s notice for the flight said the claim had been denied and the plan had paid nothing. The air ambulance company’s statement treated all $64,820 as Mara’s responsibility, even though the company was out of network and the flight followed an emergency hospital transfer.
The rural hospital’s billing office told her that the helicopter was operated and billed separately. That was true, but useless. The insurer said it had not received enough information to establish that air transport was medically necessary. A representative also told her that federal surprise-billing protections did not force the plan to cover a service it had denied.
The air ambulance billing office offered the reverse explanation: because the insurer denied the claim, the company considered the full bill collectible from the patient.
Each organization was describing its own piece of the machinery. Mara was left holding the total.
The first problem was not the price. It was the coverage decision. Her claim had been categorized as routine transport between facilities, while the medical record described a pregnancy emergency at a hospital that could not provide the required level of care.
That mismatch was hiding behind the word denied.
What federal protection covered
The No Surprises Act took effect in January 2022. For many people with private health insurance, it generally bars an out-of-network air ambulance provider from billing the patient more than the in-network deductible, copayment or coinsurance that would apply under the plan. The patient’s cost sharing must also count toward in-network limits.
The protection covers qualifying air ambulance services, including many flights between hospitals. It does not generally extend the same federal protection to ground ambulances.
There is an important catch. The law does not automatically turn every denied transportation claim into a covered benefit. If a plan says the flight was excluded or medically unnecessary, the patient can still face a coverage fight before the balance-billing protection changes the amount owed.
That distinction is defensible on paper and brutal in practice. A person caring for a newborn has to determine whether the insurer rejected the flight itself or covered the flight but processed the out-of-network charge incorrectly, although those two decisions may appear beside the same $64,820 figure.
Once Mara understood that separation, she stopped arguing about whether the bill was surprising. She focused on why the plan had treated the flight as routine.
The record that changed the claim
Mara’s discharge paperwork from the maternity center began after the helicopter landed. It documented the delivery and the baby’s hospital stay, but it did not contain the rural hospital’s full transfer record. The insurer had received records connected to the hospital claims, yet those pages had not been attached to the separate transportation claim.
She asked the rural hospital’s records office for the material created before the flight. It arrived 12 days later.
One page mattered. It documented that the local hospital could not provide the maternity care being requested, that the distant center had accepted Mara and that air transport had been selected as her condition worsened because ground travel would take more than three hours. The page connected the emergency to the helicopter in a way the air ambulance bill could not.
Mara placed it beside the $64,820 itemized bill. The service date matched. The destination matched. The 144 miles on the bill fit the transfer described in the hospital record.
Her written appeal stayed narrow. She challenged the decision to treat the flight as routine transportation and asked the plan to review the transfer record when deciding medical necessity. She also asked that, if the flight was covered, the claim be reprocessed using the federal rules for out-of-network air ambulance services.
She attached the transfer page and the itemized bill rather than sending the baby’s entire hospital chart. That choice changed where the insurer looked. Four weeks later, the portal still showed the denial, and the air ambulance company sent another statement for $64,820, so Mara asked the billing office to place collection activity on hold while the appeal was open.
The insurer then confirmed that the hospital record had been stored with the facility claim rather than the transportation claim. It sounds like a minor filing problem. It had converted a documented emergency transfer into a five-figure patient balance.
Mara also contacted the federal No Surprises help service after the new statement arrived. The service did not decide whether her flight was medically necessary, but it explained that a covered out-of-network air ambulance claim could not leave her responsible for the provider’s full billed charge. Her complaint created a separate record of the balance-billing issue while the insurer reviewed coverage.
The number finally moved
Eleven weeks after Mara submitted the appeal, the insurer reversed the denial. The flight was reprocessed as a covered air ambulance service, with her responsibility calculated under the plan’s in-network cost-sharing rules.
The new insurance notice showed an allowed amount of $23,120. The plan paid $20,980. Mara’s share was $2,140, which reflected the remaining in-network deductible and coinsurance under her coverage.
The provider later removed $41,700 from the original charge. Any disagreement over payment beyond the patient cost share belonged between the air ambulance company and the insurer, through negotiation or the federal payment dispute process. Mara was not supposed to arbitrate that fight from her kitchen.
Five months after the flight, the itemized bill was still on the table. She wrote $2,140 beside the printed total of $64,820 and kept it with the final insurance notice. The hospital and newborn claims took longer to settle.
What worked for her was the single transfer page that tied the helicopter to the pregnancy emergency, followed by a written appeal that separated the coverage denial from the federal balance-billing issue. It did not erase her cost sharing. It changed which fight was hers.
Questions people ask
Does the
No Surprises Act cover an out-of-network air ambulance?
For many privately insured patients, federal protections generally limit their share of a covered out-of-network air ambulance flight to in-network cost sharing. In Mara’s case, that protection affected the bill only after the insurer reversed its decision that the flight was not covered.
Can an insurer deny an emergency flight as medically unnecessary?
A plan can make a coverage or medical-necessity determination, even when federal balance-billing protections may apply after coverage is established. Mara’s denial changed when the insurer reviewed the sending hospital’s transfer record, which had not been connected to the separate air transportation claim.
Why were the hospital and helicopter claims handled separately?
The hospital and air ambulance company were different providers, so they submitted separate claims with different records. Mara’s receiving-hospital chart did not explain why the rural hospital selected air transport; the missing transfer page did, and attaching it to the flight claim changed the review.
Can the air ambulance company bill the full amount during an appeal?
Mara continued receiving statements while the coverage appeal was pending, but the company placed the account on hold after she documented the dispute. Once the claim was covered and reprocessed, the provider removed the balance beyond the insurer’s payment and her in-network share. Her final statement showed $2,140.
One story a day
The story of the day, in your inbox
One health journey each morning — no advice, no alarm, just company for the road.