Caring for Her Mother Cut Her Savings From $78,000 to $19,400
A mid-career daughter used unpaid leave, reduced her hours, and eventually resigned. Her notebook recorded what caring for a parent with vascular dementia cost both of them.
 Rosa DelgadoNarrator, Caregivers
August 19, 2026 · 8 min read
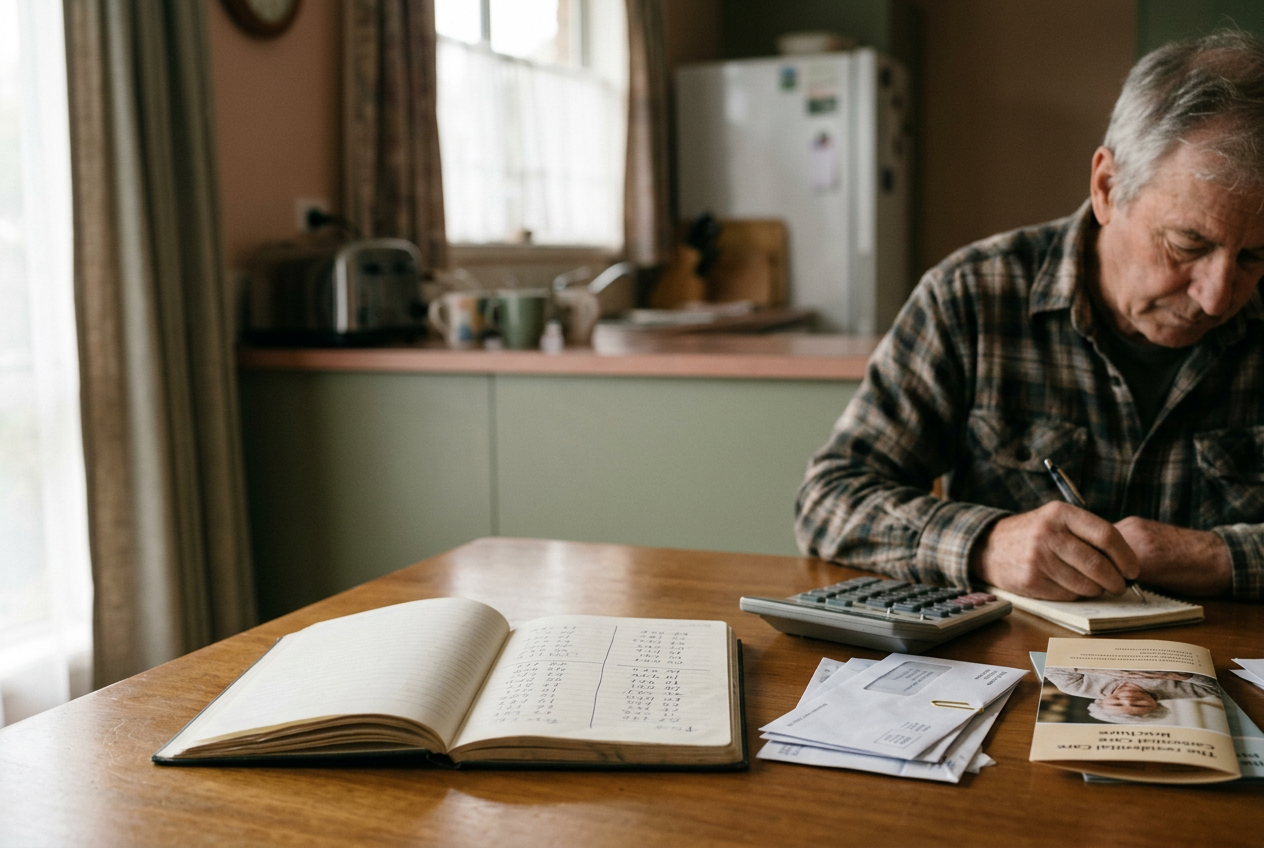
The first page of Maya’s notebook had one number at the top: $78,000. That was what she had in savings when her mother’s vascular dementia began taking up more of the week than Maya’s job could tolerate.
Maya, the daughter in this composite story, was 47 and worked as a project manager. She earned $108,000 a year, contributed enough to her retirement account to receive her employer’s full match, and had built the savings over more than a decade. Some of it was meant for a future kitchen repair. Most had no assignment.
That used to feel responsible.
Her mother lived alone nearby and received $2,820 a month from Social Security and a small pension. After a series of vascular events, she began missing payments and leaving groceries in the car. She could still discuss old family arguments in crisp detail, then call Maya twice because she could not remember where the electric bill went.
The specialist identified vascular dementia. Maya heard the diagnosis while holding the notebook, which had started as a place to write down appointment dates and medication changes. Soon she added a second section for money.
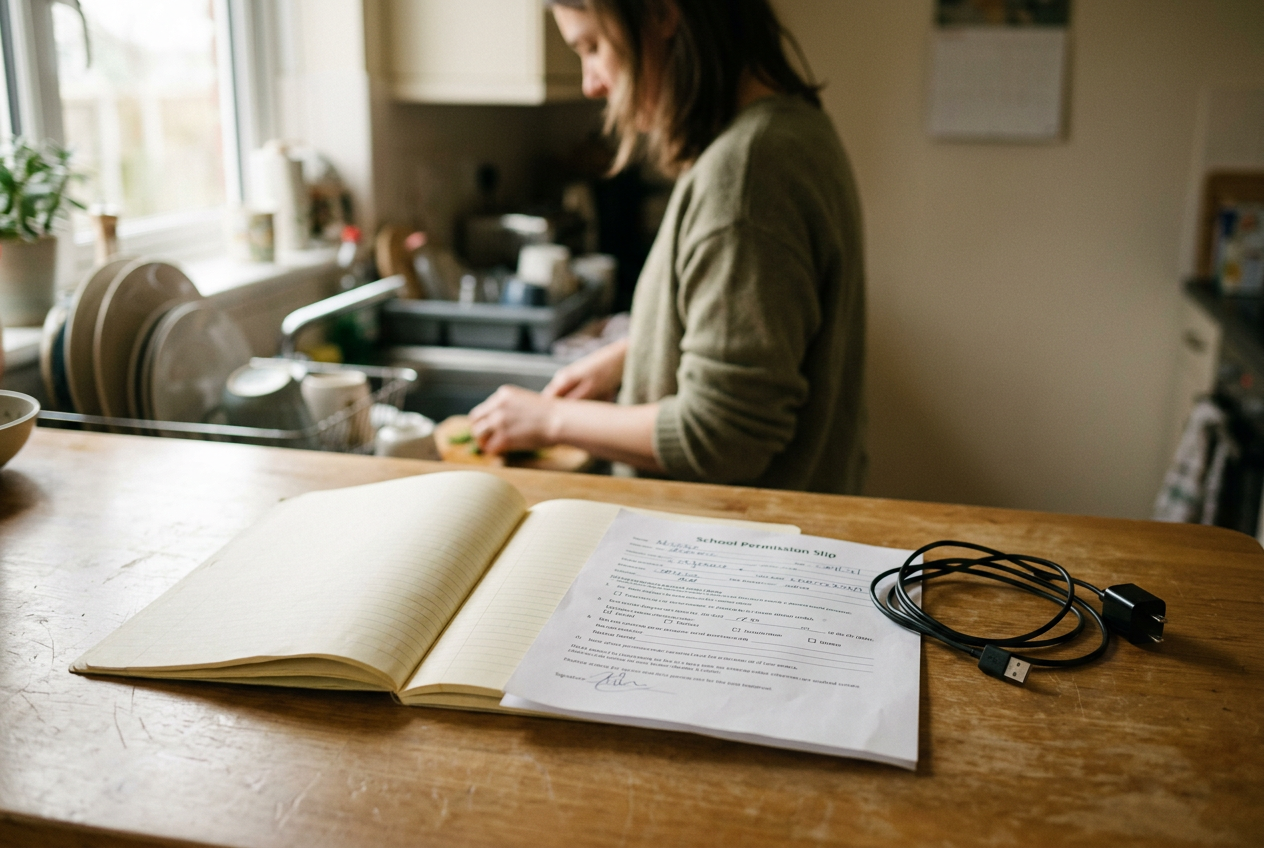
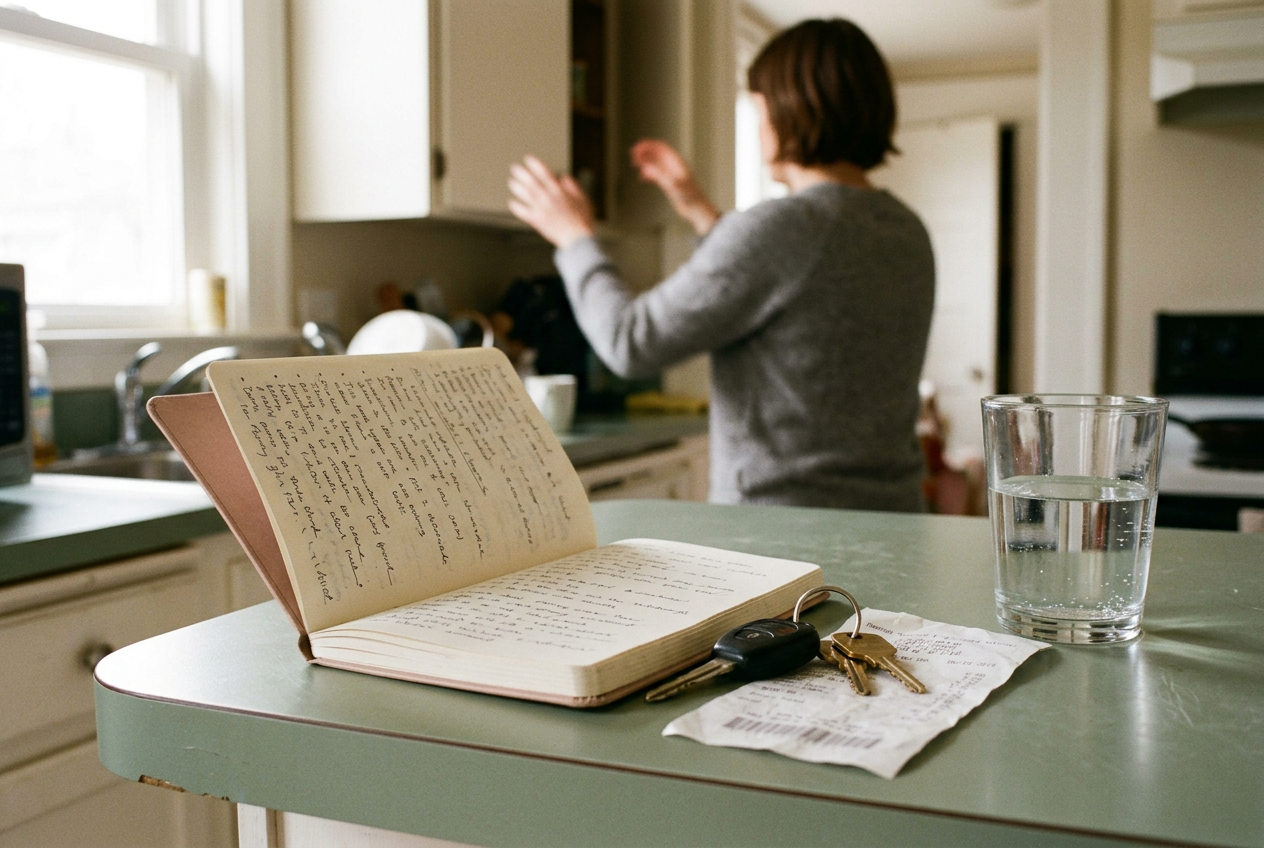
The notebook was ordinary and useful. It stayed on her kitchen table beside a calculator and a stack of mail. Expenses went on the right side of each page. Work losses went on the left, although those figures were harder to see because no one sent an invoice for a missed retirement contribution.
Leave that protected a job, not a paycheck
Maya’s employer approved job-protected family leave. She first used three weeks of paid time off, then took nine weeks without pay. The leave preserved her position for that period, but it did not replace her salary, and she still owed her usual share of health insurance premiums.
The consequential detail was not the paperwork. It was the direct deposit that did not arrive.
During those weeks, Maya arranged a home safety evaluation, attended medical visits, and toured adult day programs with her mother, who rejected each one while they were inside and later remembered liking at least one of them. Maya also began paying some household costs when her mother’s income ran short. By the time she returned to work, the notebook showed $11,760 gone from savings.
She expected returning to fix the problem. Instead, it exposed one.
Her mother could no longer be left alone for a full workday, but the adult day program operated on a schedule that did not cover Maya’s commute and meetings. A home care agency charged $31 an hour. Twelve hours a week came to about $1,610 a month, before extra coverage for appointments or the days her mother refused to get into the van.
Maya negotiated a reduced schedule at 60% of her former hours. Her salary fell with it, and she no longer qualified for the same annual bonus. She kept health coverage and continued contributing a small amount to retirement, but the employer match shrank because her contribution did.
The arrangement looked workable in an email. In practice, urgent calls arrived during the hours she was supposed to be available, while medical appointments landed on days she had promised to finish reports, and the work that disappeared from her calendar did not always disappear from other people’s expectations.
Eight months after returning, Maya withdrew $9,000 from savings to cover the growing gap. She wrote the new balance in the notebook: $57,240.
The care plan had a monthly shortfall
Her mother’s income covered housing, food, utilities, and part of the paid care. It did not cover all of it. Maya paid the remainder, which varied between $1,900 and $2,700 a month depending on how much help was needed.
There were smaller charges too, though they were not small when repeated. Transportation to appointments cost $46 on one visit and $73 on another. A door alarm was $38. Replacing food after the refrigerator was left open cost $126.
Maya stopped recording mileage after six months because the act of calculating it annoyed her more than the missing reimbursement.
She loved her mother. She also resented the checks, the interrupted work, and the way every family conversation ended with someone praising Maya for being “the capable one,” which appeared to mean that nobody else had to change a Tuesday. Both feelings fit in the car after appointments. Neither canceled the other.
At work, she turned down a project that would have required travel. A colleague received the assignment and later the promotion attached to it. Maya did not write a dollar figure for that in the notebook. She drew a line across the page and started the next month.
Her mother’s needs increased after another hospitalization. The adult day program was no longer enough, and Maya added more home care while looking at longer-term options. One assisted living community quoted a monthly fee above $7,000, with additional charges tied to the amount of help her mother needed. Maya put the brochure under the notebook and left it there for eleven days.
Medicare covered her mother’s hospital care and follow-up medical services under the terms of her coverage. It did not become a standing payment source for the daily supervision Maya was trying to arrange. Her mother had no long-term care insurance.
That distinction had been invisible to Maya when care meant appointments and a pill organizer. It became plain when care meant someone staying in the house.
A social worker changed the columns
Fourteen months into the reduced schedule, Maya met with a social worker who worked with families dealing with dementia. The most useful part of the conversation was a boundary that sounded obvious only after someone said it: her mother’s care plan could not depend indefinitely on Maya spending her own retirement money.
The social worker helped Maya separate three categories that had become tangled in the notebook: what her mother could pay from current income, what could be paid from her mother’s assets, and what Maya was choosing to contribute. Eligibility rules for publicly funded long-term support varied by state and depended on finances and care needs, so the family also obtained legal guidance about planning and decision-making authority.
This did not produce free care. It produced a more honest calculation.
Maya’s mother had $24,600 in savings, which the family had been reluctant to use because she regarded it as emergency money. Dementia was the emergency. They began using those funds for her care rather than preserving them while Maya’s account fell.
Maya’s brother, who lived several states away, agreed to pay one recurring expense and handle the billing calls he could manage remotely. It was not half the care. It was $640 a month and a set of tasks that stopped landing in Maya’s lap. She accepted the uneven arrangement because arithmetic was more useful than a debate about fairness.
The social worker also asked what would happen if Maya became sick or lost her job. There was no answer in the notebook. That blank space changed the plan more than another brochure did.
The resignation was not the final cost
Maya resigned after 18 months of trying to combine reduced work with expanding care. Her mother moved into a residential setting four months later, using her own income and assets while the family worked through longer-term funding options.
By then, Maya’s savings balance was $19,400. She had spent $58,600, though not all of that appeared as care invoices. The total included ordinary living expenses during unpaid leave and reduced employment, health insurance premiums after resigning, and money she had transferred toward her mother’s care.
There were losses outside the notebook. Maya estimated that she had missed about $14,000 in employer retirement contributions and matching funds, plus investment growth she could not sensibly calculate. Her Social Security earnings record would also reflect the lower-income years. A future employer might ask about the gap, although that cost had not arrived yet.
She began contract work once her mother’s residential care stabilized. The pay was less predictable, but the assignments had edges. She could finish one. Care had no corresponding box to check.
The notebook stayed on the kitchen table. Its final page held two balances, one for Maya and one for her mother, with a line between them. The line had come late.
Questions people ask
Does family leave pay you while you care for a parent?
In Maya’s case, job-protected leave kept her position available for a limited period but did not replace her pay. She used accrued paid time first, then had nine unpaid weeks. Leave policies, eligibility, and state programs differ, so the financial effect depends heavily on the worker’s employer and location.
Does
Medicare cover ongoing dementia care at home or in a residence?
Medicare paid for covered medical care in this story, but it did not fund the ongoing supervision Maya’s mother needed each day. The family had to combine her mother’s income and assets with paid services while exploring longer-term support. Coverage depends on the service, setting, and reason care is being provided.
Should a parent’s savings be used before a caregiver’s savings?
The social worker helped Maya treat her mother’s assets as one source for her mother’s care instead of preserving them while the daughter’s retirement money disappeared. Legal authority and public-benefit rules can affect how assets are used, and the family sought guidance specific to their state before changing the arrangement.
How can a caregiver calculate the career cost of stepping back?
Maya recorded lost wages, reduced retirement contributions, insurance premiums, and transfers toward care. She could estimate those amounts, but not the value of the promotion she missed or future investment growth. On the final notebook page, she left those entries blank and wrote $19,400 beside her own name.
One story a day
The story of the day, in your inbox
One health journey each morning — no advice, no alarm, just company for the road.