A State-Line Move Turned Her Insulin Refill Into a $684 Bill
Nina’s pharmacy app still showed her insulin after she moved for work. It did not show that her coverage, prescription and prescriber had stopped at the state line.
 Daniel ReyesNarrator, Navigating Care
August 26, 2026 · 7 min read
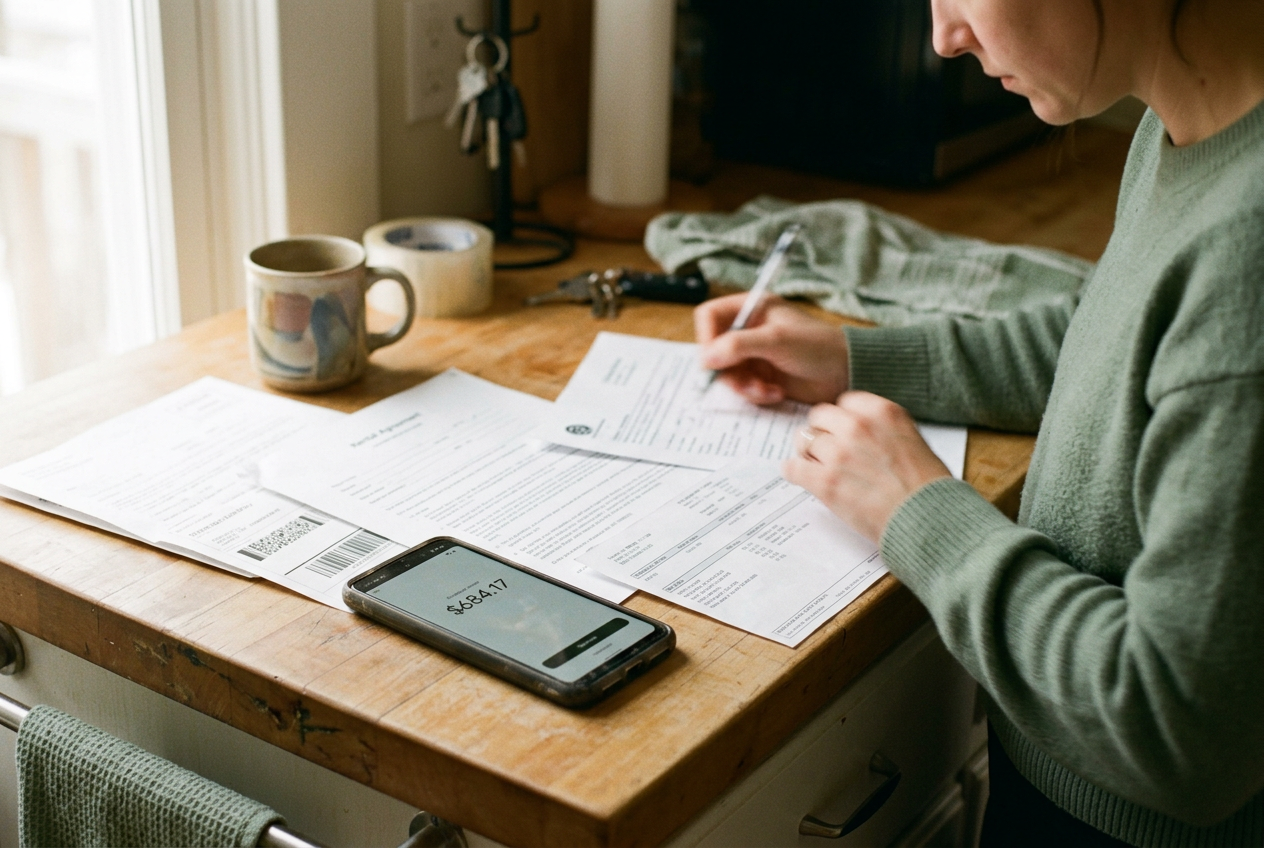
Nina moved from Nevada to Arizona in May 2023 for a hotel job paying $17.25 an hour. She had type 1 diabetes, eight days of insulin left and a start date she could not postpone without losing the position.
She also had a pharmacy app showing the medication she had picked up for years. That looked like continuity. It was only history.
Three days after unpacking, Nina requested her usual refill through the app. The request stalled, then the checkout page changed to a cash price: $684.17 due. She took a screenshot because the amount made no sense beside a medication already listed under her name.
That screenshot became her phone log. Beneath it, she typed the result of each call: old insurer, former specialist, pharmacy, new employer. Nobody had made an obvious clerical error. Each part of the system was following its own boundary, and Nina had crossed all of them at once.
The record was not the refill
The pharmacy could see that Nina had received insulin before. It could see the product and her previous pickups. What it did not have was an active prescription with refills remaining that could be used in Arizona.
This is one of the quieter traps in pharmacy technology. A national-looking app can display a medication record across locations, but that screen does not guarantee that a prescription remains valid, transferable or payable. The profile proves that something was dispensed. It does not give the pharmacist fresh authority to dispense it.
Nina’s previous prescription had reached the end of its refills. The pharmacy sent a renewal request to her specialist in Nevada, which was the same routine that had worked before the move, except Nina’s location had changed the legal setting for the care.
The specialist’s office said it could not arrange a telehealth renewal while she was physically in Arizona because the specialist was not licensed there. The issue was not that every prescription written across a state line becomes invalid. State rules and exceptions differ. In Nina’s case, the office treated the proposed visit and new prescription as care delivered in the state where she was now sitting, and its clinician did not hold that state’s license.
The pharmacy record remained visible throughout this. So did $684.17.
Three borders inside one move
Nina had bought her Nevada health plan through the individual insurance market. Its routine pharmacy coverage used a service area and network based in Nevada, and the plan would not pay this Arizona claim as an ordinary in-network refill.
Health insurance cards look portable because people carry them. Many plans are not. Emergency protections may apply in some circumstances, but they do not turn every pharmacy or clinic in another state into an in-network provider for routine care. Nina’s old premium had purchased access to a particular arrangement of clinicians and pharmacies, not a national pass.
Her move qualified her to seek new coverage outside the annual enrollment period. Under federal marketplace rules, a permanent move can create a special enrollment period, commonly extending 60 days before or after the move when the eligibility conditions are met. That gave Nina a route into another plan. It did not make a refill appear that afternoon.
She submitted proof of the move and her prior coverage, then waited for the new enrollment to take effect. Her employer’s plan was another possibility, but the job imposed a 60-day waiting period. Federal rules generally allow job-based plans to use waiting periods of up to 90 days once a worker is otherwise eligible, so the delay was not evidence that payroll had forgotten her.
All of this was administratively explainable. None of it reduced the checkout screen by a dollar.
The ugly part was the sequence. Coverage was tied to a state network. The clinician’s ability to provide care was tied to state licensure. The pharmacy’s visible history was separate from an active prescription.
Each system could point to another system and say the missing piece lived there, while Nina still had to report for hourly shifts and could not turn a week of calls into paid time.
She began keeping the screenshot open during those calls. The number stopped looking like a price and started looking like a deadline.
The bridge came from a local clinic
The pharmacy did give Nina one useful piece of information: it named a nearby community health center that saw uninsured and underinsured patients. The center did not promise a refill over the phone. It offered an appointment with a locally licensed clinician and asked for basic income information so it could assess a sliding fee.
That distinction mattered. Nina was not trying to persuade the Nevada specialist to work around a licensing problem, and she was no longer asking the pharmacy to turn dispensing history into a prescription. She was establishing care inside Arizona, even though she expected her employer coverage to begin two months later.
At the visit, the clinician reviewed her medication history and records from the former office. The clinic then sent a prescription to a pharmacy participating in its discounted medication arrangement. Nina paid $57.40 for the visit and insulin together, an amount drawn from the clinic’s income-based fee and pharmacy pricing rather than from her old insurance.
The price was not automatic, and it was not a universal rate available at every community health center. Federal programs allow certain safety-net organizations to obtain outpatient medications at reduced prices, but what a patient pays depends on the organization, eligibility and the medication. For Nina, the practical change was local: one clinician could evaluate her, one pharmacy could act on the prescription, and both were operating within the same state system.
Her new marketplace coverage took effect the following month. She canceled it after the employer plan began eight weeks into the job, then established care with an Arizona specialist so the next renewal would not return to the Nevada office.
Months later, the pharmacy app still listed the old fills. Nina kept the $684.17 screenshot anyway, directly above a photo of the $57.40 receipt.
Questions people ask
Does a pharmacy record transfer when someone moves to another state?
Dispensing history may remain visible across pharmacy locations or in an app, as it did for Nina. That does not guarantee an active prescription can be transferred or refilled. Her profile showed prior insulin pickups, but the prescription had no refills left, so the pharmacy needed a new prescription from a clinician able to provide care in her new state.
Can an out-of-state doctor renew a prescription after a move?
It depends on the clinician’s licenses, the patient’s location, state law and how the care is delivered. Nina’s former specialist would not conduct a telehealth renewal while she was in Arizona because the clinician lacked an Arizona license. Her refill moved forward after a locally licensed clinician reviewed her history and issued a new prescription.
Does health insurance keep working after a permanent move?
A plan may still exist after the member moves, but its routine network and pharmacy coverage may not extend into the new state. Nina’s Nevada plan did not pay her Arizona refill as an ordinary in-network claim. The move opened a special enrollment route, although the new coverage did not begin soon enough to solve the immediate gap.
What covered
Nina’s insulin while her new insurance was pending?
Insurance did not cover that bridge refill. A community health center assessed her income, arranged a visit with a local clinician and used its discounted pharmacy arrangement. Her experience ended with two amounts saved on her phone: the rejected $684.17 checkout screen and the $57.
40 receipt.
One story a day
The story of the day, in your inbox
One health journey each morning — no advice, no alarm, just company for the road.