Charity Care Cut His $36,782 Hospital Bill to $0
After emergency gallstone care, an uninsured patient found the nonprofit hospital’s financial assistance policy and proved that his old tax return no longer reflected what he earned.
 Daniel ReyesNarrator, Navigating Care
August 15, 2026 · 7 min read
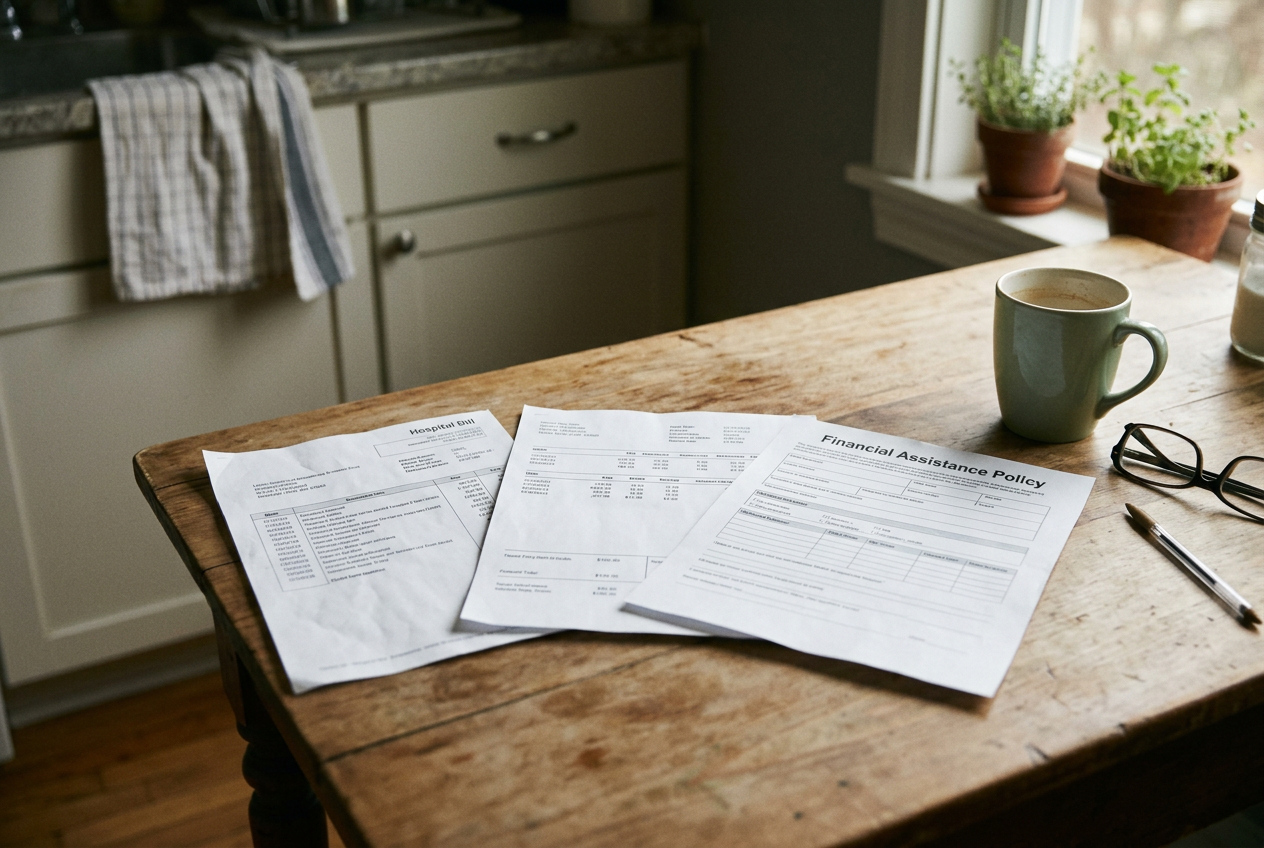
Luis kept the itemized bill on his kitchen table. It was six pages long, with $36,782.14 due after an emergency visit, imaging, two nights in the hospital and an operation related to gallstones in October 2024.
He had gone to the emergency department after the pain became unmanageable. By the time he left the hospital, he had a diagnosis, discharge papers and no idea what the care would cost. He was uninsured after losing a full-time warehouse job that had included health coverage, and his new temporary position offered none.
The first bill arrived three weeks later.
Luis understood the number at the bottom. Everything above it was harder. The itemized bill divided his care into categories that made administrative sense but did not explain why one hospital stay had produced a balance larger than what he expected to earn that year.
He called the billing office and said he could not pay $36,782.14. The first option discussed was a monthly payment plan. Even spread over several years, the proposed payment was more than his rent increase and grocery budget combined.
That conversation treated the total as fixed. It was not.
The bill arrived before the policy
A relative told Luis that nonprofit hospitals may have programs for patients who cannot afford their bills. He searched the hospital’s website and found its financial assistance policy several links away from the main billing page.
The policy used two terms, “financial assistance” and “charity care,” for reductions available to eligible patients. Charity care can sound like a favor granted after pleading. At a tax-exempt hospital, it is part of a written policy the hospital must maintain under federal rules, although each hospital sets many of its own eligibility standards.
Section 501(r) of the federal tax code requires tax-exempt hospitals to publish a financial assistance policy, limit charges for eligible patients receiving emergency or medically necessary care and make reasonable efforts to determine eligibility before using certain aggressive collection actions. The federal rule does not require every hospital to use the same income cutoff or erase every eligible bill. That freedom is doing a lot of work.
Luis’s hospital offered full assistance to a household of one with income at or below 250% of the federal poverty guideline. In 2024, the guideline for one person in the contiguous United States was $15,060, making 250% equal to $37,650.
His most recent federal tax return showed $48,900. That was what he had earned before the layoff.
His current temporary job paid an average of $612 a week, or $31,824 when annualized. The distinction was worth $36,782.14, but the bill did not point him toward it, and the first billing conversation had centered on installments rather than eligibility.
Luis returned to the itemized bill and wrote “current income” beside the total. That note became the point of the application.
One document changed the review
The hospital’s application asked for household and income information. Luis submitted it in November 2024 with his tax return and recent pay stubs, then asked the billing office to place the balance on hold during the review.
Nineteen days later, he received a notice saying the application lacked enough information. The $36,782.14 still appeared in his online account.
At first he read that notice as a denial. It was closer to an administrative stop: the hospital had his old annual income and some evidence of his new wages, but it had not accepted the file as a complete picture of the job loss and current earnings.
This is where financial assistance systems become needlessly punishing. A patient can provide truthful documents, meet the written income limit and still receive a notice that looks final, because the office reviewing the application has not connected the older tax return to the person’s present circumstances.
Luis called again. He did not retell the medical story. He focused on the mismatch between the $48,900 tax return and the $31,824 annualized income shown by his current pay.
The representative said the hospital could review more recent evidence of income and job separation. Luis sent the layoff notice and six current pay stubs, along with a short written explanation that he lived alone and no longer had the job shown on his tax return.
He also included the relevant page from the hospital’s own policy, where the eligibility table placed a one-person household under $37,650 in the full-assistance category. The policy was dense, but the math was not.
That page mattered more than another description of hardship would have. Luis was not asking the hospital to invent an exception. He was showing that the documents already placed him inside the hospital’s published limit once the reviewer used current income.
The itemized bill remained on the table during the six-week review. Luis checked the portal, saw the same amount and worried that the account hold might disappear before the application was decided. He did not make the proposed monthly payment because he had been told the balance was paused, though the hospital continued sending routine statements generated by its billing system.
Those statements made the hold feel theoretical. The amount due never changed.
The adjustment covered the hospital bill
In January 2025, the hospital approved full financial assistance for the eligible hospital services. The adjustment reduced the $36,782.14 balance to $0.
Luis received the decision in writing. Several days later, the online account caught up. He opened the itemized bill again and compared its total with the zero balance on the portal, partly because he had spent ten weeks being told by one system that the application was under review while another kept presenting the full debt as payable.
The approval covered the hospital’s charges from the emergency episode. It did not create health insurance, cover later care elsewhere or guarantee that an outside physician group would use the hospital’s policy. Hospitals can contract with clinicians or groups that bill separately, and the financial assistance policy is supposed to explain which providers participate, though that information is often buried in another document.
Luis had one smaller outside bill connected to the hospital stay. The hospital’s adjustment did not erase it. He contacted that billing office separately and arranged a reduction based on uninsured status, leaving a balance he paid over four months.
That unresolved split is part of what hospital billing language hides. A patient experiences one emergency and one hospital stay, but the financial system may treat the episode as several unrelated debts, each with its own rules and review.
For the main bill, what worked in Luis’s case was narrow and concrete: he used the nonprofit hospital’s written income threshold, documented what he earned after losing his insured job and asked the office to review current income instead of relying on the older tax return. He kept the decision with the six-page itemized bill.
Questions people ask
Can an uninsured patient apply for hospital financial assistance after receiving a bill?
Luis applied after his first statement arrived, while the entire $36,782.14 was still due. The hospital reviewed the application and paused the account during that process. Federal rules for tax-exempt hospitals provide an application period that generally extends 240 days from the first post-discharge billing statement, but hospital policies and timelines vary.
Does a nonprofit hospital have to erase every bill?
No. Tax-exempt hospitals must publish financial assistance policies and follow federal billing protections, but they set many eligibility rules, including income limits and the services covered. Luis received full assistance because his current annualized income fell below his hospital’s published threshold for a one-person household.
Can the hospital use an old tax return after someone loses a job?
Luis’s hospital initially reviewed a tax return showing $48,900, which no longer represented his circumstances. The application moved forward after he supplied his layoff notice, recent pay stubs and a written explanation. His hospital accepted current annualized income of $31,824, but its policy controlled that decision.
What finally reduced the hospital balance to zero?
The hospital matched Luis’s current income documents to its own 250% poverty-guideline threshold, then approved full assistance for the eligible hospital charges. Ten weeks after he submitted the first application, he placed the approval letter beside the itemized bill and refreshed the portal. It showed $0.00.
One story a day
The story of the day, in your inbox
One health journey each morning — no advice, no alarm, just company for the road.