Overturning an Insurance Denial for Chemo Scalp Cooling
When an Ohio teacher was billed $2,250 for scalp cooling during breast cancer chemotherapy, her insurer called it cosmetic. An external review proved otherwise.
 Daniel ReyesNarrator, Navigating Care
August 5, 2026 · 5 min read
In October 2022, a 34-year-old English teacher from central Ohio was sitting in a hospital infusion room, listening to her oncologist explain a chemotherapy plan to treat her stage II breast cancer. The treatment was supposed to last 16 weeks and would likely cause her to lose all her hair within 21 days, unless she used a special scalp cooling system to reduce blood flow to her hair follicles. However, the hospital didn't have this equipment in their supply room, and she had to contact a medical device company directly to get it. The company charged her $2,250, which she paid with her personal credit card, and then they shipped the cooling caps to her home.
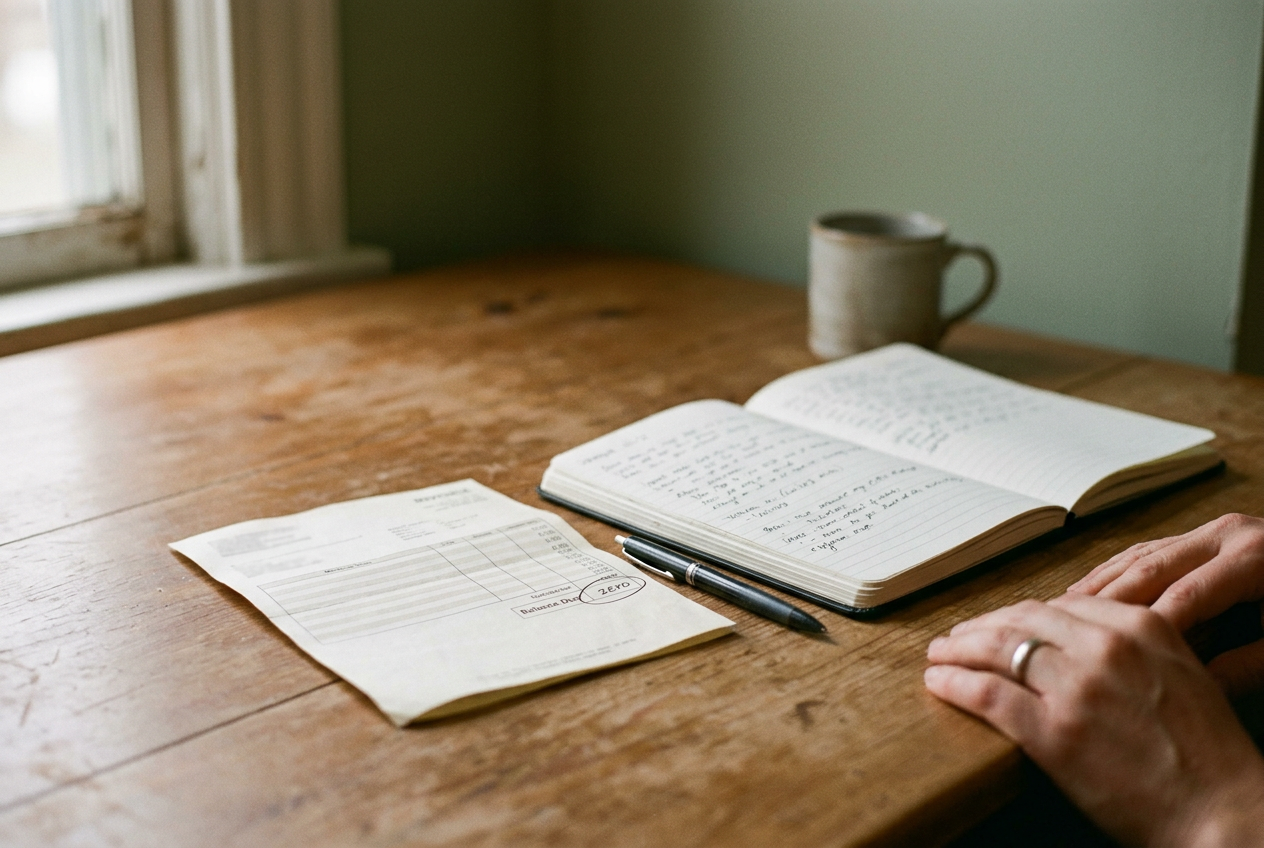
She also bought a notebook to keep track of all her interactions with her health insurance company, knowing it could get complicated. As she began her treatment, she was aware that navigating her insurance coverage would be just as important as fighting her cancer. She was determined to stay on top of things, logging every phone call, email, and conversation with her insurance provider, to make sure she got the care she needed without breaking the bank.
Scalp cooling works by reducing the temperature of the scalp by a few degrees immediately before, during, and after chemotherapy infusions, which narrows the small blood vessels serving the hair roots and limits the cellular uptake of toxic drugs. FDA clearance for these automated cooling systems arrived years ago, and national cancer treatment guidelines recognize scalp hypothermia as an effective intervention for reducing drug-induced alopecia. When the teacher submitted her claim for reimbursement, her insurer issued a swift denial letter that classified the entire procedure as cosmetic. In insurance jargon, cosmetic means any service the corporate medical policy team deems unrelated to vital organ function, a designation that transforms evidence-based supportive care into a personal luxury expense.
The term cosmetic hides a deeper administrative reality that has very little to do with clinical outcomes or patient well-being. By categorizing scalp cooling as an aesthetic choice rather than a prophylactic medical treatment, insurers avoid establishing standardized reimbursement rates, shifting thousands of dollars in equipment costs and nursing setup time directly onto patients who are already facing enormous medical bills. The denial letter she received also included the word investigational, creating a double-barreled administrative wall where a treatment is simultaneously labeled an unnecessary beauty service and an unproven science experiment.
She opened the black lined notebook on her kitchen table and recorded her first official call to the customer service line printed on the back of her insurance card in November 2022. The representative on the line confirmed that her policy had no specific billing category for scalp hypothermia, which meant any incoming claim containing those service descriptions automatically routed to a hard denial code. When she asked how to challenge the ruling, the agent suggested submitting a formal first-level internal appeal with supporting letters from her care team, though he warned her that internal appeals regarding non-covered benefits rarely succeeded without explicit state mandates.
Her oncologist drafted a detailed letter of medical necessity explaining that hair preservation was directly tied to patient psychological stability, treatment adherence, and privacy during active therapy, particularly for a classroom teacher who wanted to continue working without disclosing a life-threatening diagnosis to teenagers. The physician attached four peer-reviewed studies demonstrating hair retention rates above sixty percent for her specific drug protocol, alongside clinical proof that the cooling system was cleared by federal regulators. The billing department at the cancer center bundled these documents with the original itemized invoice and submitted the package before the end of the month.
In January 2023, two months after the initial decision, the insurance company sent a brief letter to the teacher, saying that the new evidence didn't change their mind about covering cosmetic services. The teacher wrote down the denial date in her notebook, underlined it, and then scheduled a meeting with the hospital's financial advisor. During this meeting, she found out that a lot of patients give up after the first denial because dealing with paperwork and insurance issues is extremely hard when you're already feeling very sick, tired, and in pain. The teacher was determined to keep fighting, but she was also aware of the challenges that lay ahead, and how overwhelming it can be to navigate the complex world of medical insurance while dealing with serious health issues.
The financial advisor walked us through the next part of the process, which meant going around the insurance company altogether. We could do this by getting an independent external review. According to federal healthcare laws and insurance rules in Ohio, if a health plan says no to covering something because of a medical decision, or says it's experimental, or not necessary, the patient has the right to take their case to a panel of independent doctors outside of the insurance company. What they decide is final and the insurance company has to follow it.
This way, we avoid the conflict of interest that can happen when the insurance company reviews its own decisions. But, it's not easy - the patient has to put together a complete medical file and get it in on time, which can be tough.
In March 2023, the teacher worked with her clinic's social worker to put together an appeal to the state insurance department. They sent in a big packet of information that included her chemotherapy schedule, notes from the nurses about how long she used the cooling system during treatments, guidelines from cancer experts, and a detailed list of what she paid out of pocket. She kept track of the mail delivery confirmation number in her notebook, waiting for the state to assign an independent cancer doctor to look over her records.
In May 2023, the woman finally got the decision from the external review, which came seven months after she started chemotherapy and eight weeks after she finished her treatment. Luckily, she still had most of her hair. The independent medical reviewer looked at her case and decided that the insurance company was wrong to deny her claim. They said that the scalp cooling treatment she got was a medically appropriate way to deal with the physical side effects of her chemotherapy.
Because of this decision, the insurance company had to go back and process her claim again, this time covering the cost of the treatment as a medical benefit. They also had to send her a check for $2,250 to refund her for the treatment and update her deductible so it reflected the payment.
The issue wasn't resolved because the insurance company suddenly felt sorry for her, but because she pushed hard for an independent medical expert to review the evidence. This expert looked at the case outside of the insurance company's automatic denial system. In the end, she got her reimbursement check and her invoice was paid in full. The whole process was recorded in her notebook, from start to finish.
It showed the date she got the check and that her balance was finally zero. The insurance company's system didn't automatically fix the problem, so the next patient in that infusion chair might face the same issues. It took her persistence to get the claim resolved, not a change of heart from the insurance company.
Questions people ask
How did she appeal the insurance denial for scalp cooling?
She logged every insurance interaction, obtained a medical-necessity letter and supporting studies from her oncologist, and submitted an internal appeal. After that was denied, she worked with her clinic's social worker to send a complete case file to the state insurance department for independent external review.
Why did the external reviewer decide scalp cooling should be covered?
The independent medical reviewer concluded that scalp cooling was a medically appropriate way to manage a physical side effect of chemotherapy. That finding overturned the insurer's classification of the treatment as cosmetic or investigational.
Did the teacher get reimbursed for the scalp cooling system?
Yes. After the external review, the insurer reprocessed the claim as a medical benefit, refunded the $2,250 she had paid, and updated her deductible.
One story a day
The story of the day, in your inbox
One health journey each morning — no advice, no alarm, just company for the road.